Menu
Date Published: March 21, 2023 (Updated October 29, 2026)
Table of contents :
Sometimes bills don't wait for your next paycheque. A payday loan can cover the gap, but it's worth understanding how a cash advance works before you borrow. This guide breaks it all down in plain language, from what payday loans cost in Canada to who qualifies and the rules that protect you.
A payday loan is a small, short-term loan that you usually pay back from your next paycheque. In Canada, you can borrow up to $1,500, and the most a lender can charge is $14 for every $100 you borrow. You have up to 62 days to repay.
Payday loans are unsecured, which means you don't have to put up something you own, like your car, to get one. Instead, lenders look mostly at your income and whether you can pay the loan back. Each province sets its own rules and decides which lenders are allowed to offer these loans.
TL;DR

Payday loans in Canada are short-term, unsecured loans of $100 to $1,500, typically repaid on your next payday, within 62 days at most. They’re legal and regulated by each province. The cost is $14 per $100 borrowed: borrow $300, repay $342. iCash is a licensed direct lender in Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario and Prince Edward Island, offering instant decisions 24/7 and funds sent by Interac e-Transfer® within 2 minutes of signing.
How do payday loans work? The process is pretty straightforward. Here’s what happens from start to finish:
Apply. You fill out a short application online, sharing some details about your income and your bank account.
Get a decision. Licensed online lenders usually give an instant decision, which is why these loans are often called instant loans.
Review your agreement. Before you sign anything, the lender must show you the full cost of the loan in writing, including the fee and the APR (annual percentage rate).
Receive your money. Once you sign, the funds are sent to your bank account, often by Interac e-Transfer within minutes.
Repay on payday. On your due date (or dates, if your loan is paid back in installments), the lender collects the payment from your bank account through a pre-authorized debit (PAD).
There are two things to know before you apply. First, your bank account needs to accept pre-authorized debits. Second, licensed lenders offer only one loan at a time, so you’ll need to pay off your current loan before taking out another. If terms like APR or PAD are new to you, our list of payday loan key terms explains them in plain language.
People often turn to payday loans as car repair loans, dental loans, medical loans or or a way to get emergency funding when a bill can’t wait.
Picture this: it’s -30°C in Winnipeg, your car won’t start and the repair shop wants $800 to fix it, but your next paycheque is still a week away. A one-time, urgent expense like this is what payday loans are designed for. Borrowing $800 would cost $112 in fees, so you’d repay $912.
How much does a payday loan cost? In Canada, a lender can charge at most $14 for every $100 you borrow. If you repay on time, that fee is the full cost of your loan, and nothing else is added on top.
Here's what that looks like for different borrowing amounts:
Amount Borrowed | Fee ($14 per $100) | Total to Repay |
$100 | $14 | $114 |
$300 | $42 | $342 |
$500 | $70 | $570 |
$1,000 | $140 | $1,140 |
$1,500 | $210 | $1,710 |
Because the fee is a flat $14 per $100, you can work out your total before you apply, and borrowing only what you need keeps your cost down. If you're thinking about a $500 payday loan online in Canada, our step-by-step guide covers the cost and how to apply. If you need less than that, a smaller loan may be a better fit for you.
Your loan agreement will also show an APR, or annual percentage rate. APR shows what a loan would cost if you kept it for a full year, so you can compare it with other types of credit.
Because payday loans last weeks, not a year, the APR can look very high, even though your fee stays the same. The APR isn't an extra fee. It's the same $14 per $100, shown as a yearly rate. A longer term means a lower APR, but the dollar amount you pay doesn't change.
Here’s how that looks in the official cost disclosures for three provinces, as an example:
Ontario: On a $500 loan of 14 days, the total cost of borrowing is $70, with a total payback amount of $570 and an APR of 365%. On a loan of 62 days, the APR is 82.42%.
Nova Scotia: On a $100 loan for 14 days, the total cost of borrowing is $14, with total payback amount of $114 and an APR of 365.00%.
Prince Edward Island: On a $300 loan of 14 days, the total cost of borrowing is $42, with a total payback amount of $342 and an APR of 365.00%. On a loan of 62 days, the APR is 82.42%.
Want to see your exact numbers? Use our payday loan calculator to work out your cost before you apply.
With most payday loans in Canada, you repay the amount you borrowed, plus the fee, in one payment on your next payday. Your due date is set around when you get paid, and the term can be no longer than 62 days. If your next pay is a few weeks away, aloan with a one-month term gives you a little more time between borrowing and repaying.
Some provinces have their own repayment rules:
Ontario: If it’s your third loan within 63 days, you can repay it in installments instead of one lump sum.
Alberta: Every payday loan is repaid in installments. Terms run from 42 to 62 days, with 2 to 7 payments depending on how often you’re paid. Our page onAlberta’s payday loan rules explains this in more detail.
If one lump-sum payment feels like a stretch, an installment loan lets you split it up. With iCash, an installment loan follows the same rules as a payday loan. You can borrow $100 to $1,500, the cost is still $14 per $100, and the full amount is repaid within 62 days.
The difference is that your repayment is spread across 2 or 3 of your upcoming paydays (or 2 to 7 in Alberta) instead of one. Each payment is collected automatically by pre-authorized debit.
For example, if you borrow $600 and repay in 3 installments, your total cost is $84, so you’d repay $684 in three payments of $228. (legal to confirm if payments are split evenly).
Splitting your repayment doesn’t change what you pay overall. It means a single paycheque doesn’t have to cover the whole amount, which can make it easier to keep up with your other bills. Availability and the number of payments depend on your province. You can see how installment loans work in your province for the details.
Generally, payday loans win on speed and access: you can borrow quickly, often with less focus on your credit history. Over longer periods, though, they cost more than other types of credit.
Here's how they compare with other loan options:
Payday Loan | Traditional Installment Loan | Traditional Personal Loan | Line of Credit | |
Typical amount | $100 to $1,500 | Larger amounts than a payday loan | Larger amounts than a payday loan | A set credit limit you can draw from |
Duration | Up to 62 days | Several months or longer | Several months to several years | Ongoing, no fixed end date |
How cost is charged | $14 for every $100 borrowed | Interest, capped at 35% APR | Interest, capped at 35% APR | Interest on the amount you use, capped at 35% APR |
Credit requirements | Income and ability to repay carry the most weight | Credit check; terms depend on your credit | Credit check; terms depend on your credit | Credit check; usually requires good credit |
Funding speed | Often within minutes of signing with online lenders | Varies by lender | Varies by lender | Once approved, you can draw funds as needed |
Best used for | Small, one-time emergencies you can repay from your next pay | Larger expenses you want to repay over time | Planned or larger costs | Ongoing or unpredictable expenses |
A quick note on names: iCash installment loans and iCash personal loans aren't the same as the traditional installment loans and traditional personal loans in this table. They're payday loans of $100 to $1,500 at the same $14 per $100, repaid in 2 or 3 payments instead of one (or 2 to 7 in Alberta), depending on your province.
Why the difference in cost? Under the Criminal Code, most consumer loans, including traditional installment loans, personal loans and lines of credit, can't charge more than 35% APR, the federal criminal interest rate since January 1, 2025.
Payday loans are exempt from that limit because they're regulated by the provinces and capped at $14 per $100. Over a few weeks, that flat fee can make sense for a small, urgent expense. Stretched over months, the cost adds up quickly.
If you're weighing your options, you can read more about our personal loans in Canada, learn how a line of credit works, or compare otheronline money loans available to Canadians.
To qualify for online payday loans, you must be of legal age in your province, have a steady income and have a valid Canadian bank account. Most applicants get a decision instantly.
Getting a payday loan online with us is quick and easy! Select your desired loan amount, repayment plan* and provide a few personal details.
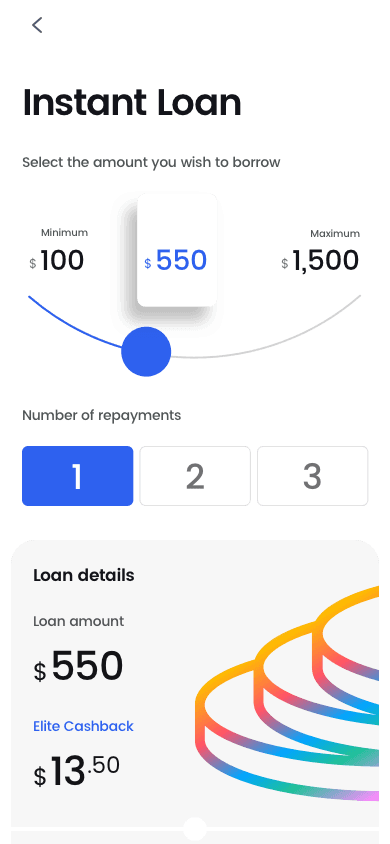
Our online payday loan application will tell you if you’re approved instantly. If you are, you just need to electronically sign your agreement. That’s it!
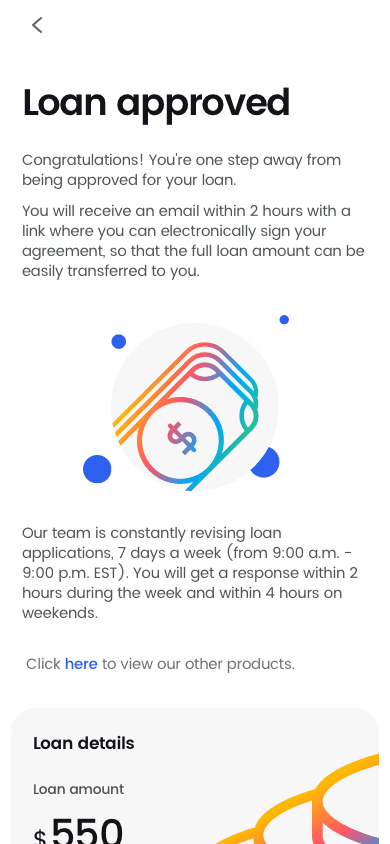
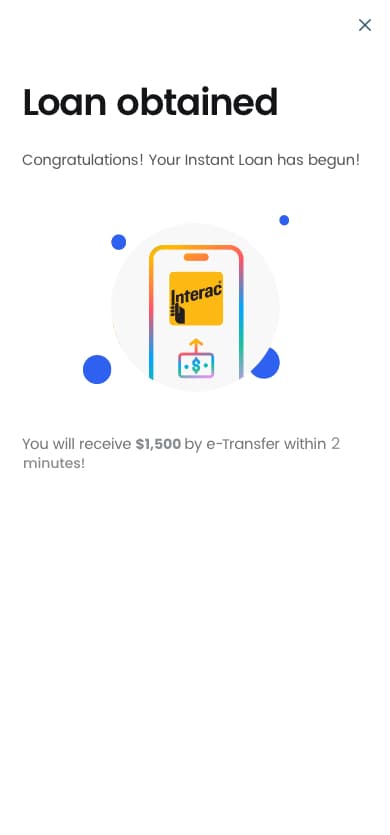
Once you digitally sign your agreement, your payday loan will be sent by Interac e-Transfer® within 2 minutes. Funds are sent 24/7, no matter what.
To apply for a payday loan with iCash, you must:
Be at least 18 years old (19 in British Columbia, New Brunswick and Nova Scotia)
Live in a province where we operate: Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario or Prince Edward Island
Have received income from the same source for the past three months
Have a total net income of at least $800 per month
Have an online bank account that accepts pre-authorized debits*
Have a valid Canadian mobile phone number, address and email address (VoIP numbers aren't accepted)
*KOHO accounts don't qualify because they don't support pre-authorized debits.
For a full breakdown, see what you need to qualify for a payday loan.
Your income counts, whether it comes from a job, self-employment, a pension or a government program. If government benefits are your main source of income, you can still apply. We accept a wide range of programs.
Federal benefits include the Canada Pension Plan (CPP), Old Age Security (OAS), Employment Insurance (EI) and the Canada Child Benefit. These support retirees, people between jobs and families with children.
Provincial programs include Ontario Works, the Ontario Disability Support Program (ODSP) and Alberta’s Assured Income for the Severely Handicapped (AISH). These provide income support for people with low income or a disability.
No matter where your income comes from, we look for two things: you’ve received it from the same source for at least three months, and your total net income is at least $800 per month.
Whatever your income source, the same two rules apply. You need to have received it from the same source for at least three months, and your total net income needs to be at least $800 per month. If government benefits are your main source of income, our page on payday loans with government benefits explains how the process works for you.
Applying online takes just a few minutes, and you won't need to visit a store or fax any documents. Have these ready before you start:
Your full name, date of birth and home address
A valid Canadian mobile phone number and email address
Details about your income, including where it comes from and when you're paid
Access to your online bank account
Here's what to expect once you apply:
Decision: You'll get an instant decision.
Funding: If you're approved, your money is sent by Interac e-Transfer within 2 minutes of e-signing your agreement.
Availability: You can apply 24/7, including evenings, weekends and holidays, so same-day loans are possible even outside business hours.
Your first application includes a credit check. After that, future loans don't require one, which is one of the benefits of being a returning customer.
Bad credit isn't automatically a barrier. When you apply for a short-term loan, your income and your ability to repay carry the most weight, so a low credit score doesn't rule you out on its own.
If your credit history has been a concern in the past, learn more about loans for people with bad credit. You can also check your credit score for free with iCash's Credit Health service.*
*Finabanx Ltd. and iCash are not affiliated with Equifax Canada Co. Equifax® is a trade-mark of Equifax Canada Co. used under license.
Who you borrow from matters as much as the loan itself. With direct lender payday loans in Canada, one licensed lender approves, funds and services your loan from start to finish. Brokers forward your application to several lenders, and cash advance apps offer a different type of product, so it helps to know what to expect before you apply.
Direct Lender | Broker | Cash Advance App | |
Who funds the loan | The lender you apply with | One of the lenders your application is sent to | The app provider |
Licensing | Licensed as a payday lender in each province where it lends | Varies by province; the lender that funds your loan is licensed | Can vary by product and province |
Typical amounts | $100 to $1,500 | Depends on the lender you're matched with | Usually smaller advances |
How cost is charged | $14 per $100 borrowed (for payday loans) | Set by the lender that funds your loan | Often a monthly subscription or optional tips |
Who sees your application | The lender you apply with | Each lender your application is sent to | The app provider |
Keep in mind that the difference between these options is how the loan is funded, not how you apply. Many direct lenders also let you apply through their own mobile app. As a licensed direct lender, iCash funds and services every loan itself. To see the difference in practice, read about how iCash compares to other lenders or loans that are like iCash.
It’s normal to feel apprehensive about sharing personal or banking information online. Here’s how your information is protected when you apply.
Your information is encrypted. This means, everything you share is protected with 256-bit SSL-encrypted, bank-level security, whether you apply on our website or through the iCash mobile app. Always download the app from the official App Store or Google Play.
Your application stays with one company. As a licensed direct lender, we don’t pass your application to other lenders or brokers.
You see everything before you agree. Licensed lenders must show you the full cost of your loan in writing before you sign.
Your money arrives quickly and securely, 24/7. Funds are sent by Interac e-Transfer straight to your bank account within 2 minutes of e-signing, even on nights, weekends and holidays. Each transfer is processed through your bank’s secure banking system, so your account details are never shared in the notification you receive. You can learn more about how Interac e-Transfer payday loans work and why they’re a fast, secure way to get your funds.
When you choose a licensed lender and apply through its official website or app, payday loans online can be a safe and secure way to borrow. The warning signs and license check below can help you confirm who you’re dealing with.
Most people never come across a lending scam, but it's worth knowing the warning signs, especially if you’re new to borrowing.
Walk away if a lender does any of the following:
Charges a fee before you get your loan
Promises "guaranteed approval"
Doesn't show a license number or business address
Wants payment in gift cards or cryptocurrency
Pressures you to sign right away
Charges more than $14 per $100, the legal maximum in Canada
Learn more about the warning signs of lending scams or read our fraud protection FAQs.
Feature | iCash |
Fully Online | ✅ |
Instant Interac e-Transfer | ✅ |
Transparent Pricing | ✅ |
Available 24/7 | ✅ |
Licensed Direct Lender | ✅ |
Speed & Convenience: No commute to storefront locations or lengthy paperwork. Apply from anywhere using our website or mobile app, available on iOS and Android platforms.
Transparent & Affordable: We have a clear fee structure at $14 per $100 borrowed for instant loans, which is compliant with Canadian laws. No hidden charges or surprise costs. You’ll know precisely what you need to pay for your loan before you sign any agreement with us.
See a real example — here's exactly what a $500 payday loan costs
Trusted & Licensed: Fully licensed, with over 1 million satisfied customers. Rated 4.5/5 on Google, and a proud member of the Canadian Consumer Finance Association.
Exclusive Perks: Earn up to 12% cashback on borrowing costs. Returning customers enjoy faster re-loan processing, increased borrowing limits, and no additional credit verification.
"Not sure if a payday loan is right for you? See how iCash compares to other options.
If you're weighing a payday loan against a personal loan or line of credit, our online money loans in Canada guide breaks down which option fits which situation.
Payday loans are legal in Canada. Each province licenses and regulates payday lenders, and the Criminal Code allows funding of $1,500 or less with terms of 62 days or less in provinces that have their own laws.
Here's how those rules work and what they mean for you.
Payday lending in Canada is regulated at two levels: federal and provincial.
At the federal level, the Criminal Code sets the maximum interest rate for most loans. Since January 1, 2025, that limit, called the criminal interest rate, has been 35% APR. Payday loans are treated differently. Under section 347.1 of the Criminal Code, the 35% limit doesn't apply to a payday loan if all of the following are true:
The loan is for $1,500 or less
The term is 62 days or less
The lender is licensed in the province
The province has been designated by the federal government because it has its own laws to protect borrowers and limit the cost of borrowing
Payday loans still have a federal cost limit. Since January 1, 2025, the Criminal Interest Rate Regulations have capped the cost of a payday loan at $14 per $100 borrowed in every province with a payday loan law. This replaced the different limits provinces used to set, so borrowers now pay the same maximum wherever they live.
At the provincial level, each province licenses payday lenders and sets its own protections, including cooling-off periods, repayment rules, limits on fees for missed payments, and how you can file a complaint. A lender needs a license in every province it operates, including if it only operates online.
Here's how the rules compare in each province we operate in:
Province | Max cost | Term / repayment | Cooling-off | APR example | Regulator |
|---|---|---|---|---|---|
Alberta | $14 per $100 borrowed | 2–7 repayments, 42–62 days | 2 business days (verify) | 82.42% (62 days) | |
British Columbia | $14 per $100 borrowed | 2-3 repayments, 62 days | 2 business days (verify) | Verify | |
Manitoba | $14 per $100 borrowed | 2-3 repayments, 62 days | 48 hours (verify) | Verify | Manitoba Consumer Protection Office (CPO). |
New Brunswick | $14 per $100 borrowed | 2-3 repayments, 62 days | 2 business days (verify) | Verify | Financial and Consumer Service Commission of New Brunswick (FCNB). |
Nova Scotia | $14 per $100 borrowed | 1 repayment, 62 days | 2 business days (verify) | 365% (14 days) | |
Ontario | $14 per $100 borrowed | Single repayment; installments available on 3rd loan in 63 days | 2 business days (verify) | 365% (14 days) / 82.42% (62 days) | |
PEI | $14 per $100 borrowed | 2-3 repayments, 62 days | 2 business days (verify) | 365% (14 days) / 82.42% (62 days) |
Payday loan rules by province vary in the details, but every province gives borrowers the same core protections.
Before you sign→ your lender must give you a written agreement that shows the cost of borrowing, the APR, the total you'll repay and your due date.
After you sign→ you can cancel during the cooling-off period for any reason. Just return the money you borrowed, with no fee or interest. Licensed providers can't give you a second loan while your first is outstanding, and they can't roll your balance into a new loan.
In Ontario, you can repay your third loan within 63 days in installments. In Alberta, every loan is repaid in installments, but you can pay it off early or in one lump sum at any time without a penalty.
If something goes wrong→ fees for a missed payment are capped by law. If you think a lender hasn't followed the rules, contact them first, then your provincial regulator, listed in the table above.
Checking a lender's license takes only a few minutes. Here's how to do it:
Find the license number. Licensed lenders list their license number for each province, usually in the website footer.
Check it with your provincial regulator. Look up the lender in your province's online registry of licensed payday lenders, or contact the regulator directly. You'll find each province's regulator in the "Rules by province" table below.
Confirm the legal business name. The name on the license should match the company you're dealing with. For example, iCash is operated by Finabanx Ltd.
Confirm a Canadian business address. A licensed lender should list a physical address in Canada. iCash's head office is at 372 Bertha Street, Suite 102, Hawkesbury, Ontario, K6A 2A8.
Here are iCash's current license numbers:
Province | License Number | Expiry |
|---|---|---|
Alberta | #341941 | Oct. 31, 2028 |
British Columbia | #67639 | Oct. 31, 2027 |
Manitoba | #74162 | May 1, 2027 |
New Brunswick | #180004440 | May 3, 2027 |
Nova Scotia | #262535468 | July 31, 2027 |
Ontario | #4733142 | March 17, 2027 |
Prince Edward Island | #40955 | March 23, 2027 |
Payday loans are an expensive way to borrow, and many people end up taking out another loan soon after repaying the first. According to the Financial Consumer Agency of Canada, half of payday loan users were repeat borrowers, meaning they took out two or more payday loans over three years.
Understanding why that happens is the best way to make sure a payday loan works for you, not against you. Our guide to borrowing money responsibly is a good place to start.
The cycle usually starts with a small gap. When your loan is due, the full amount plus the fee comes out of a single paycheque. That can leave you short on rent, groceries or bills, so you borrow again to cover the gap, and the pattern repeats.
Here's a simple example. Sam borrows $500 to cover a dental emergency. On payday, $570 comes out of his account. That leaves him $570 short for the next two weeks, so he borrows another $500. He does this four times in a row. After about two months, he has been charged $280 in fees, and he still has a $570 payment coming up.
Each loan on its own was small and paid back on time. The cost added up because he took them out back to back. This is why it’s worth knowing the rules on taking out more than one payday loan before you borrow again.
If there isn't enough money in your account on your due date, the pre-authorized debit will fail. Your bank may charge you a non-sufficient funds (NSF) fee, but new federal rules limit how much. Federally regulated banks can't charge more than $10, can't charge more than one NSF fee within 2 business days on the same account, and can't charge one at all if you're short by less than $10.
The lender will then try to collect what you owe. They'll contact you to set up payment, and provincial rules limit how and when they can do that. If the debt stays unpaid and is sent to a collection agency, it may affect your credit.
The most important thing to do is contact your lender before your due date if you know you'll be short. Most lenders would rather work out a solution with you than send your loan to collections. For practical tips, read our guide on how to manage a payday loan.
A payday loan isn’t the right fit if you're short every month, if you keep falling behind on rent or mortgage payments, if you want to pay off other debts, or if the money is for something that can wait. It's also worth pausing if repaying the loan on your next paycheque would leave you short again, because that's how the debt cycle starts.
In those situations, other options are often a better match. Some employers offer a pay advance, so you can get part of your next paycheque early without paying a borrowing fee. Many credit unions offer small personal loans with longer repayment terms and lower interest.
If a specific bill is the issue, contact the company directly. Utility providers, phone companies and landlords will often agree to a payment arrangement or a short extension. You can also read about alternatives to payday loans and whether they’re worth it.
Take a moment to check whether any of these sound familiar:
☐ You take out a new loan right after repaying the last one
☐ You've used one loan to pay off another
☐ You've skipped groceries, bills or other essentials to make a repayment
☐ You've used a payday loan in most of the past few months
☐ You borrow from more than one lender to get by
☐ You're not sure how much you owe in total
If you checked one or more, there’s free help available. Non-profit credit counselling agencies, like the members of Credit Counselling Canada, offer free, confidential advice on budgeting and managing debt. You can also see our list of credit counsellors who can help with bad credit. The Financial Consumer Agency of Canada also has free resources on payday loans and their alternatives.
We're licensed to lend in seven provinces, and the rules are a little different in each one. Find your province below for local rules and cities, or browse all the locations we serve.
Province | Good to Know | Major Cities |
|---|---|---|
Every loan is repaid in 2 to 7 installments over 42 to 62 days. | Calgary, Edmonton, Red Deer | |
If it’s your third loan within 62 days, you can repay it over 2 or 3 pay periods. | Vancouver, Surrey, Victoria | |
You can cancel within 48 hours, not counting Sundays and holidays. | Winnipeg, Brandon | |
Every lender, including online-only lenders, must be licensed by FCNB. | Moncton, Saint John, Fredericton | |
Loans are repaid in a single payment, and online loans can be cancelled within 48 hours of receiving the money. | Halifax, Dartmouth | |
If it's your third loan within 63 days, you can repay it in installments. | Toronto, Ottawa, Mississauga | |
You can cancel up to the end of the second day after signing. | Charlottetown, Summerside |
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Read more reviews.
Have more questions? Check out our full FAQ.
Master payday loan management with smart budgeting and debt reduction tips. Learn all the strategies to get ahead financially. Take charge of your money now!... Read more
Find the answer to the question “How Many Payday Loans Can I Get?” Learn about regulations, provincial limits, and get tips for responsible borrowing. ... Read more
Compare 7 payday loan alternatives in Canada, from cash advance apps to credit unions. See real costs, speed, and eligibility so you can pick what fits.... Read more
Need a $500 loan in Canada? Borrow $500 and repay $570. Licensed lender, Interac e-Transfer funding, apply 24/7. See if you qualify in minutes.... Read more