Menu
Date Published: April 6, 2023 (Updated October 12, 2026)
Table of contents :
A direct lender assesses your payday loan application, lends its own money, holds your loan agreement, and collects your repayment itself, with no broker or lead-generation site standing between you and your funds. iCash is a licensed direct lender in Canada. iCash funds every loan it approves, holds the agreement itself, and collects repayment directly, so you always know exactly who you're dealing with.
Key Takeaways

A direct lender lends its own money and holds the loan agreement. No outside company ever sees or handles your submission.
Brokers or lead-generation sites work differently. In this case, they collect your information and then forward or sell it to other lenders, sometimes several at once.
iCash operates under Finabanx Ltd., licensed to lend in Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario, and Prince Edward Island.
Borrowing $500 from iCash costs $70 ($14 per $100 borrowed), for a total repayment of $570.
iCash lends up to $1,500 and only within the seven provinces where it holds a licence.
A direct lender is a company that reviews your loan request, lends its own money, holds your loan agreement, and collects amount due itself, from start to finish.
Three things separate a direct lender from a broker or a lead generator.
The first is who holds the licence: they carry a provincial lending licence issued in its own name. The second is who holds your loan agreement: with a direct lender, that agreement sits between you and one company, not a network of undisclosed partners. The third is who you repay: the credit provider collects your payment itself and applies it to your own account.
You can confirm a lender's status with four questions:
Who actually approves my loan?
Whose name is on the loan agreement?
Who do I send my payment to?
What provincial licence number can you give me?
A direct lender answers all four plainly, using its own name each time.
A direct lender lends and services its own loans. A broker or lead generator collects your application and passes it along to someone else for a fee. Knowing which one you're dealing with tells you who's actually approving your loan and who you'll owe money to once it's funded.
Who lends the money | The company itself | A third-party provider it matches you with | Whichever provider ends up buying your loan request. |
Who holds your application data | The company you applied to, and no one else | Shared with the lenders in its network | Often sold, sometimes to more than one buyer |
Who you repay | The same company that approved you | The loan provider you were matched with | Whoever your data was sold to |
Licence required | Yes, in its own name, for lending | Varies by province and business model | Frequently none |
How they get paid | Interest and fees on the loan itself | A referral or matching fee from the credit provider. | A fee for each application it sells |
Where complaints go | The loan provider’s provincial regulator | Can be unclear when more than one company is involved | Often unclear, since the data has changed hands |
With a broker or lead-generation site, you're not necessarily applying to just one credit provider. Your information may be passed along to several lenders, and if each checks your credit, one submission can result in multiple inquiries.
Complaint routes get harder to follow too, since it isn't always clear which company actually holds your agreement once your data has changed hands. Because the lead-generation model doesn't require a lending licence, it also leaves more room for unlicensed operators to collect loan requests behind a legitimate-looking form.
Both the Financial Consumer Agency of Canada and your provincial consumer protection authority recommend confirming a funding provider’s licence before you apply. Working with them keeps your data with one licensed company and your loan agreement with the same company that approved you.
For a closer look at how these models get misused, see our guide on warning signs of lending scams.
Yes. iCash is a licensed direct loan provider in Canada, operating under Finabanx Ltd. with provincial lending licences in Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario, and Prince Edward Island.
When you apply with iCash, iCash reviews the application, iCash funds the loan, and iCash collects the repayment. Nothing gets forwarded to another company, and the loan agreement is between you and iCash alone. You can confirm this licence directly with your province's payday lending regulator using the legal name Finabanx Ltd.
As one iCash customer in Ontario explained after her second loan, the part that stuck with her was that the same company that approved her submission was the one she made her payment to. This way, there was no new company contacting her in between.
That's the practical difference a direct lender makes, and it's also the checkable one: a licence in the loan provider’s own name, an agreement with that same name on it, and an amount due that goes to that same name.
iCash charges $14 per $100 borrowed on its small loans. Borrow $500, and the cost is $70, for a total payment of $570.
The annual percentage rate depends on your loan term because a short-term rate looks very different when stated on a yearly basis. On a 62-day term, the $14-per-$100 cost works out to an APR of 82.42%. On a 14-day term, that same rate works out to an APR of 365%.
Payday loans are only exempt from Canada's Criminal Interest Rate Regulations when a credit provider is licensed under its province's payday lending rules, which is part of why the licence itself is worth checking before you borrow.
iCash lends up to $1,500 per loan. Approval isn't guaranteed, conditions apply, and iCash offers one loan at a time.
You can work out your own numbers with our payday loan calculator before you apply.
iCash holds licences in seven provinces: Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario, and Prince Edward Island. iCash doesn't lend outside these provinces, so if you live anywhere else in Canada, your loan request won't go through.
Terms, fees, and repayment structures aren't identical across all provinces—each one sets its own payday lending rules through its own consumer protection authority. A resident of Nova Scotia and a resident of Alberta won't necessarily see the same repayment schedule for the same loan amount. Ontario and Nova Scotia require a lender to disclose the loan's APR before you sign, which is why the APR figures above matter most if you're borrowing in one of those three provinces.
Check your own province's page for the exact terms that apply where you live:
To apply with iCash, you need to have reached the age of majority in your province, live in one of the seven licensed provinces, have a recurring source of income, and hold an active Canadian bank account. That income can come from steady employment, self-employment, or recurring benefits, as long as it's regular and you can verify it.
iCash looks at more than a credit score when it reviews a loan request, which is part of why applicants with imperfect credit can still apply, including those exploring our bad credit loan options.
Approval isn't guaranteed, and we assess every submission on its own. Your first loan includes a credit check as part of that review. If you've borrowed from iCash before, a returning application doesn't need another credit check, which is one practical benefit of building a repayment history with a loan provider rather than a new broker each time.
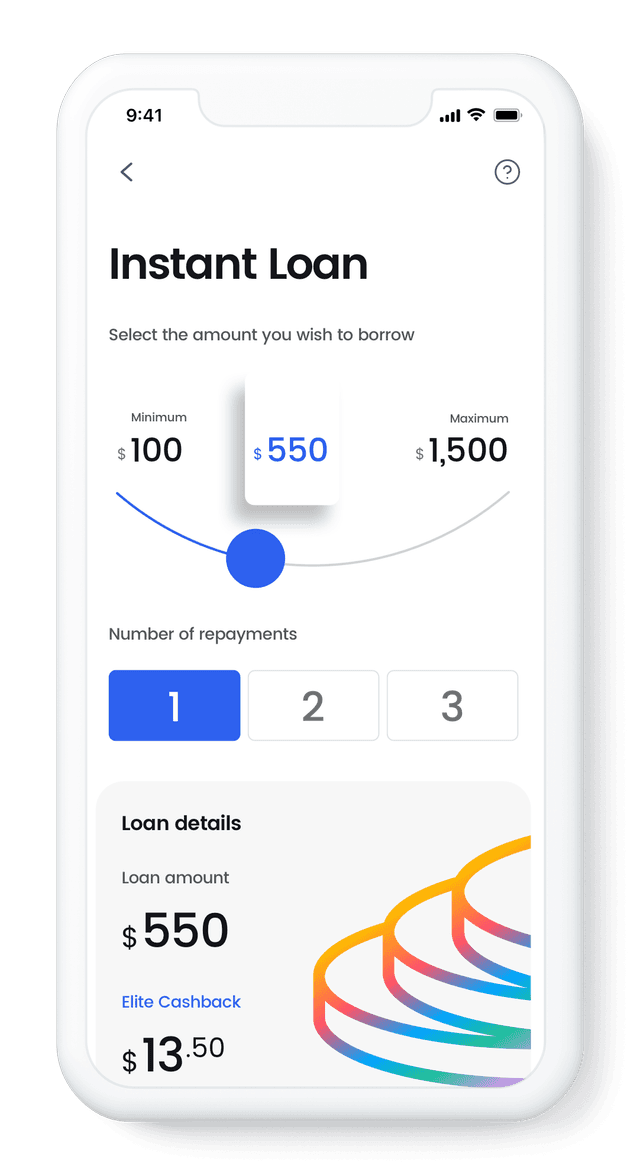
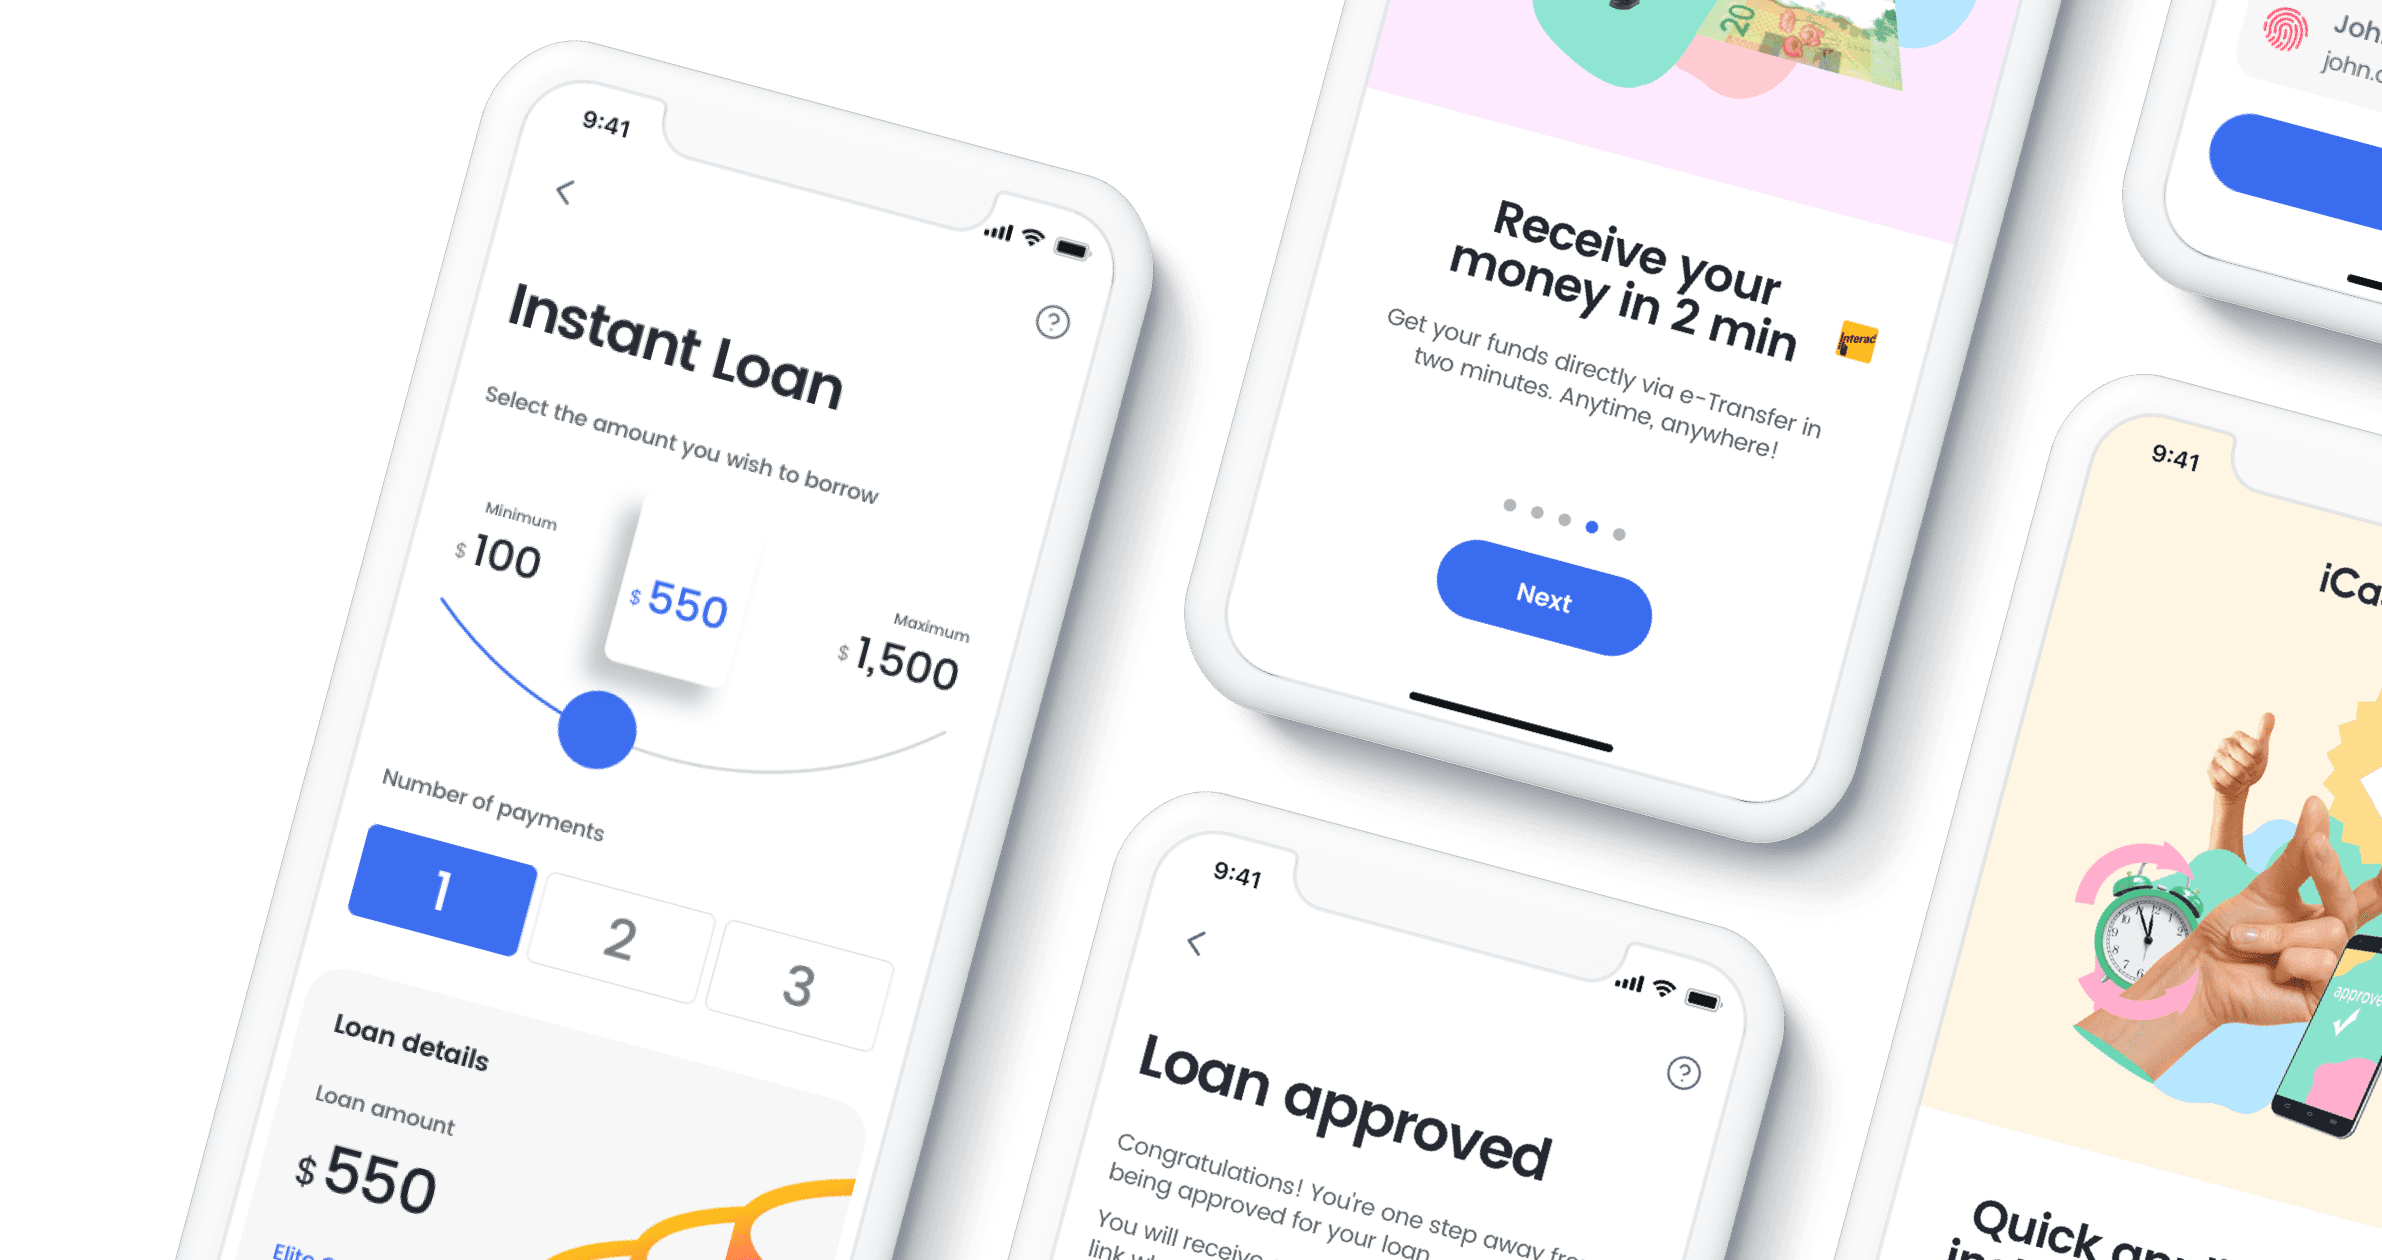
Getting an online loan with us is fast and easy. Simply select your loan amount, repayment plan* and provide some personal details.
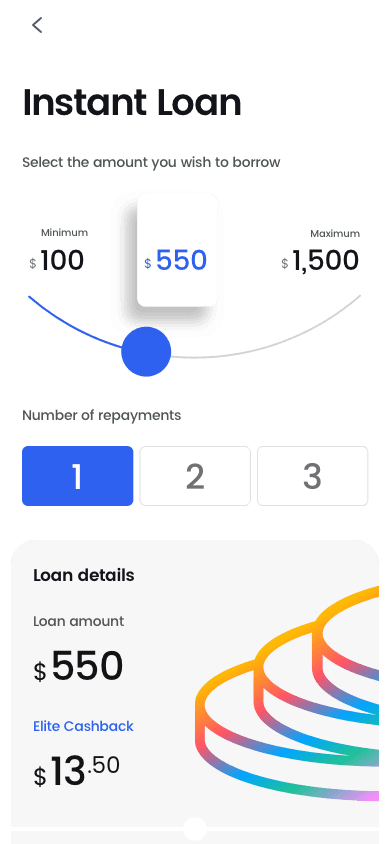
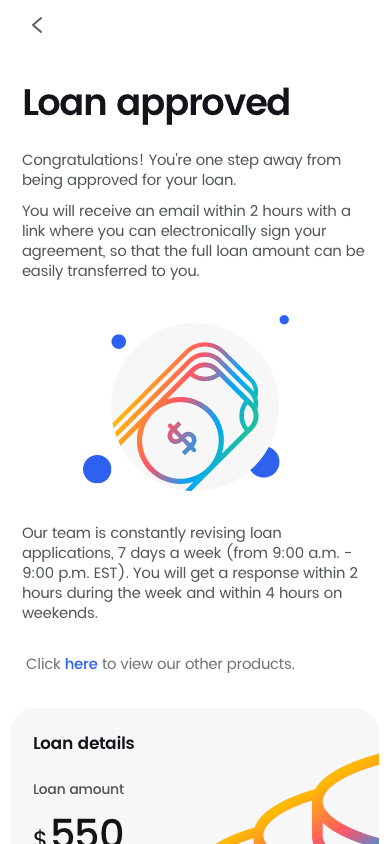
Our online loan application will tell you if you’re approved instantly. Once approved, all you have to do is electronically sign your contract. It’s that easy!
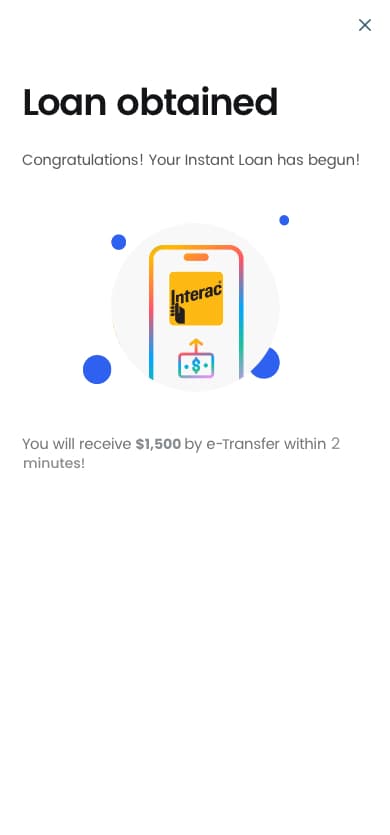
Once you sign your digital agreement, your cash advance will be sent by Interac e-Transfer® within 2 minutes. Fast, convenient and hassle-free. Funds are sent 24/7, no matter what.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Read more reviews.
Have more questions? Check out our full FAQ.