
No refusal installment loans exist in Canada. But they don’t mean what you may think.
A “no refusal” loan doesn’t mean every single applicant is always approved and funded. A legitimate lender must check your eligibility and ability to repay. In Canada, payday lenders must be licensed and follow the rules of the province or territory where they operate.
So if you see an ad that promises approval “no matter what,” take the time to check what's actually being offered before you jump in. Let’s see why…
Key Takeaways

No legitimate lender can guarantee every single applicant will be approved for a loan.
The term “no credit check” does not necessarily mean the lender never performs any kind of credit verification.
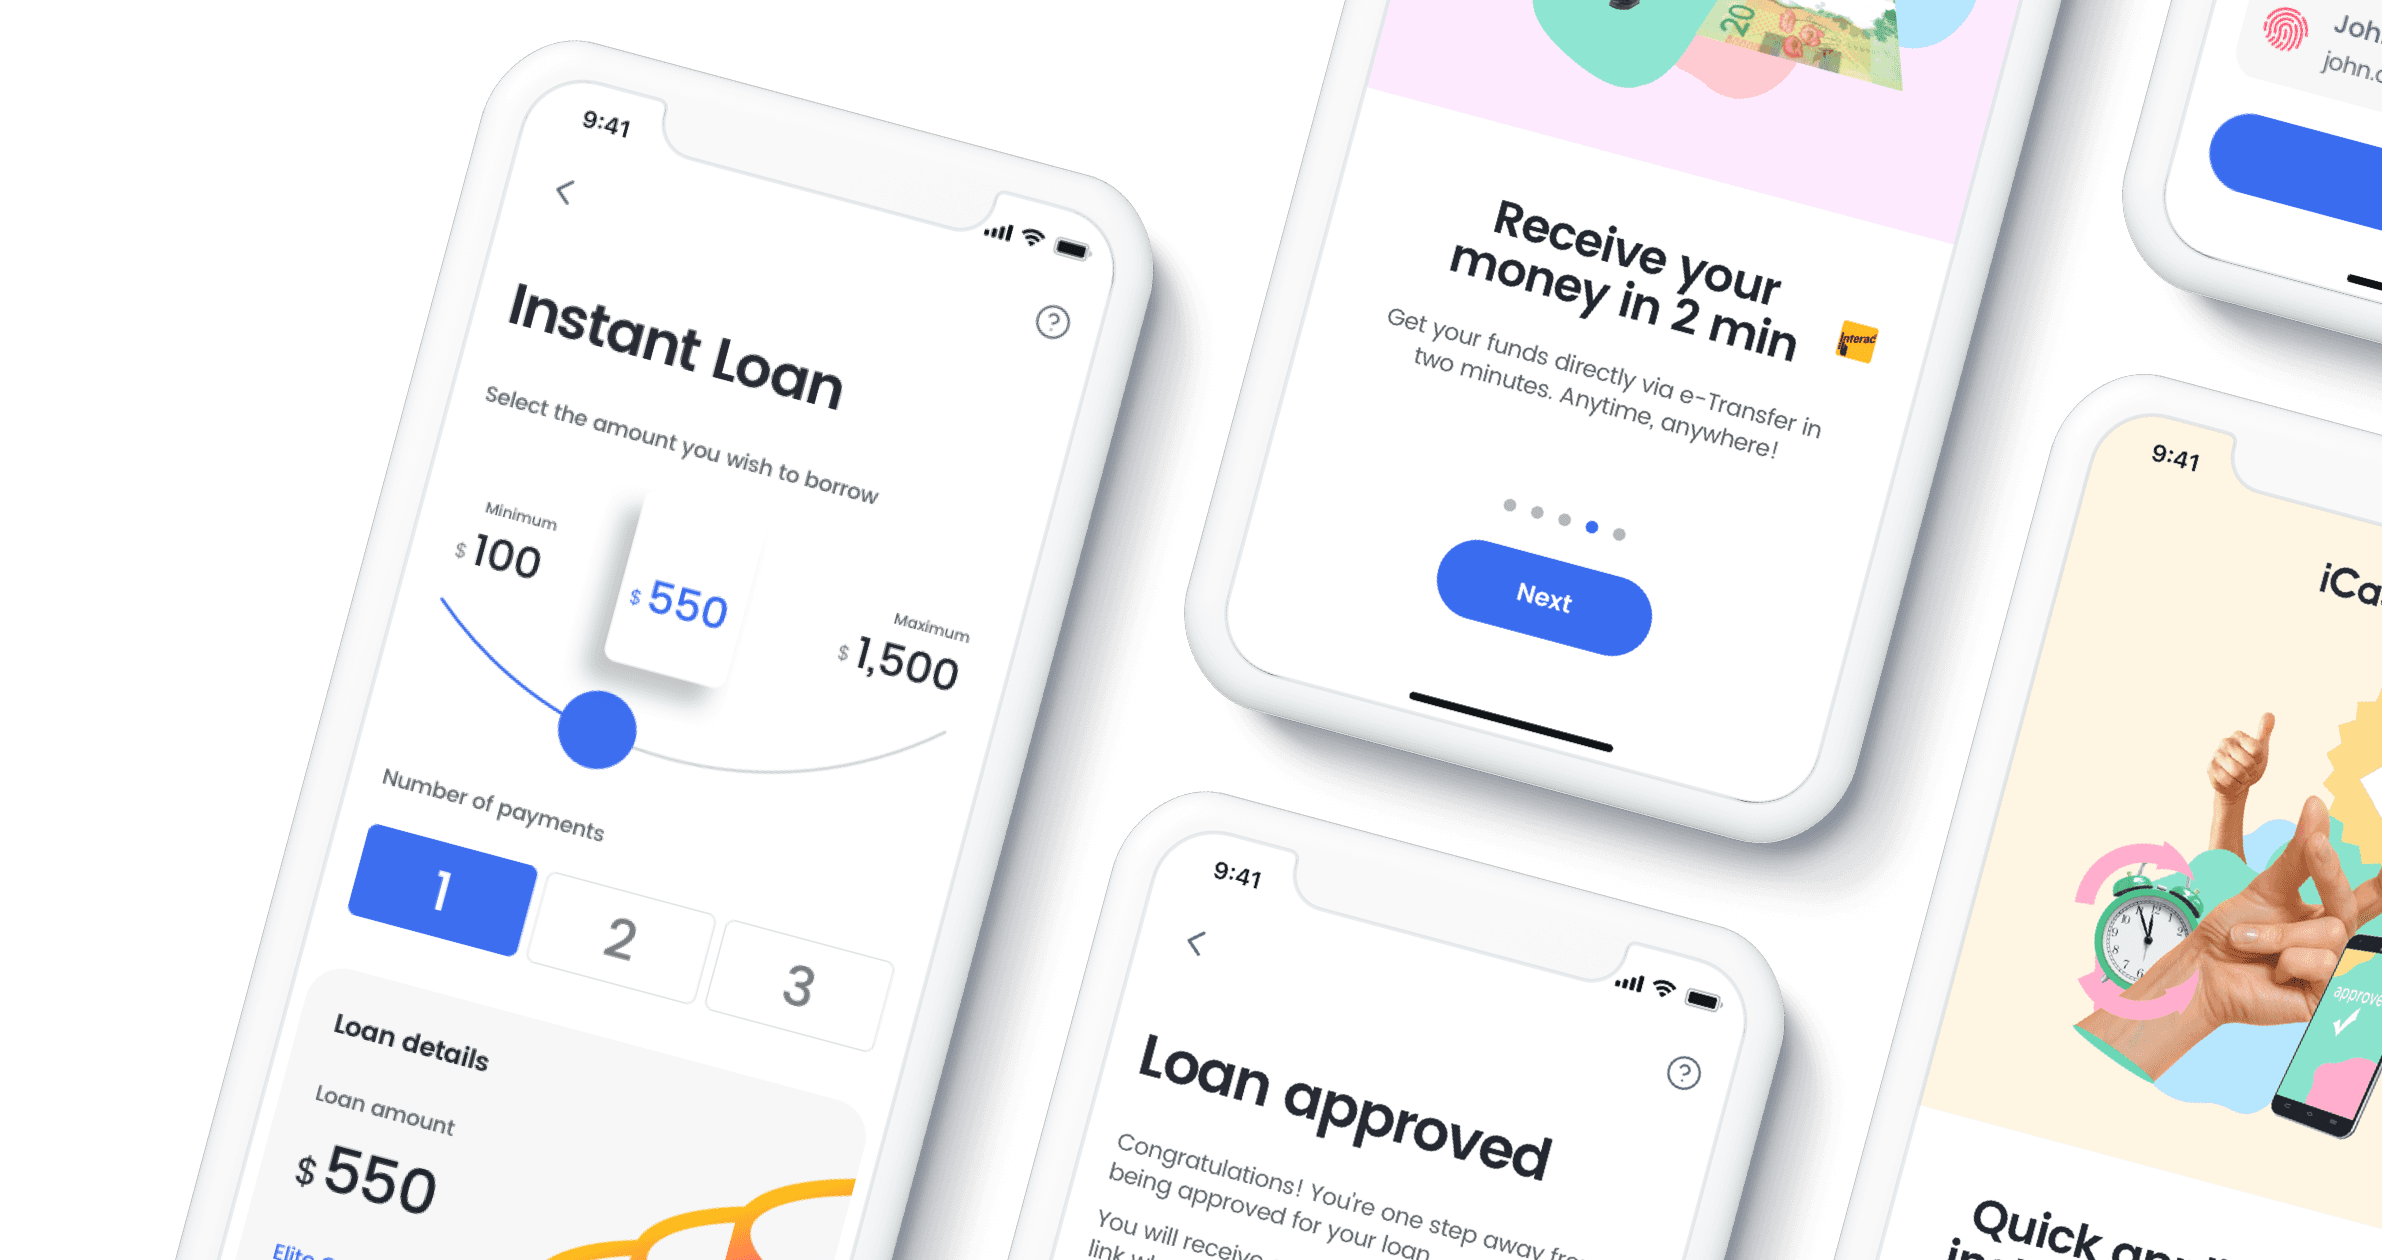
iCash completes a credit check on your first application; any subsequent applications do not require another credit check. iCash charges $14 per $100 borrowed regardless of your credit score.
Installment loans usually use multiple scheduled payments to repay what you borrowed. Payday loans are generally paid back in one lump sum or a limited number of payments, depending on your provincial rules.
What “No Refusal” Funding Actually Means Here?
“No refusal” loans or funding options are not a special type of loan under Canadian lending law. The phrase “no refusal” is simply marketing language for loans with more flexible approval criteria. This does not mean these loans have no approval or qualification process.
This distinction matters, especially to those who may have recently been declined when looking for a quick loan.
High approval rates and guaranteed approval are not the same thing. A lender may serve borrowers who don't qualify for traditional bank financing while still reviewing income, banking information, repayment ability and other eligibility requirements. Treat a “no refusal” claim that removes all conditions carefully.
What Does “No Credit Check” Actually Mean Here?
Does this mean lenders never check your credit? Not necessarily.
When people search for installment loans with no credit check in Canada, they may mean one of two things:
They don't want a lender to rely on their credit score when making a decision.
They don't want their credit file checked at all.
Those are not the same thing.
A licensed lender may consider factors beyond a credit score, including income and other information supplied during an application. For those with a bad credit score looking for fast funding, lenders who consider multiple factors may read past a poor credit score.
Canada’s Financial Consumer Agency of Canada notes that payday lenders may offer loans without a credit check, but applicants can still be expected to provide regular income, a bank account and other information.
At iCash, the current process is more specific: we conduct a credit check on the first loan application, while second and subsequent applications do not require another credit check. Approval is not guaranteed.
So “no credit check” should never be interpreted as “no questions asked” or “automatic approval.”
Installment Loans vs. Payday Loans — Which Is This?
The difference between an installment loan and a payday loan is the repayment structure. Both are loans and require an application.
An installment loan generally divides your payments across multiple scheduled payment dates. A payday loan is designed for short-term borrowing repaid in one lump sum around your next payday. You may be able to break up a payday loan into multiple payments to spread the repayment cost. This depends on provincial rules, which vary across Canada.
Installment loan | Payday loan | |
Repayment structure | Multiple scheduled payments | Usually one payment or a limited number of payments |
Typical term | Longer than a traditional payday loan; varies by lender | Typically up to 62 days |
Typical amount | Interest and fees vary by lender and product | Generally up to $1,500 |
The labels can be confusing because rules vary by province.
For example, iCash currently offers payday loans in Alberta with terms of 42 to 62 days and 2 to 7 payments, depending on income frequency. In Ontario, the standard structure is one repayment, except for a specific third-loan situation within 63 days.
So if you're searching for easy approval installment loans in Canada, look beyond the product name. Check the actual payment schedule, total cost and term to understand what you're being offered.
How Approval Actually Works
So, how do you apply for a loan without getting denied?
Before applying for any online personal loan, you need to understand how the lender reviews your application and what they look at.
Licensed payday lenders generally require information such as regular income, a bank account and a permanent address. For borrowers with damaged or limited credit, this can matter because a credit score is only one part of their financial picture.
For example, someone might have a low score because of missed payments several years ago but now have regular employment income. Someone else might have little traditional credit history but a predictable source of income.
That doesn't mean either applicant is automatically approved. It means that a lender's decision may involve more than simply asking whether the applicant has a “good” credit score.
This is also why no refusal loans Canada shouldn't be understood as loans with no eligibility requirements. The useful question is what those requirements are and whether the costs fit your budget.
Red Flags: How to Spot a Risky Loan Offer
When you're under financial pressure, “guaranteed approval” can sound reassuring, right? When you have an unexpected expense, a “guarantee” of funding can be really attractive. That's exactly when it's worth taking a breath and checking the details.
Watch for offers that:
won't show the total cost of borrowing before you agree
ask you to send an upfront payment before receiving the loan
promise approval regardless of income, debt or other circumstances
pressure you to provide banking information before you understand the agreement
The Financial Consumer Agency of Canada recommends checking that a payday lender is licensed in your province or territory. It also notes that a payday loan agreement should identify important information such as the amount borrowed, fees, payment schedule and due date.
The 4-Question Test for Any “No Refusal” Loan
With many lenders advertising “no refusal loans” and “guaranteed approval,” here's how you can vet them before pursuing a quick loan. Ask four simple questions.
1. Is the lender licensed?
Check the lender's provincial licence through your province or territory's consumer protection resources. A legitimate lender should be willing to identify itself.
2. Am I being asked to pay before I receive the loan?
Be cautious if you're told to send money first to “unlock,” “insure,” or “release” your loan. Understand exactly what you're paying and why before sending money.
3. Do I know the total cost?
Don't focus only on the amount deposited into your account. Check the fee, total repayment amount, payment dates and applicable APR disclosure. Consider how this loan will affect you over the next few months.
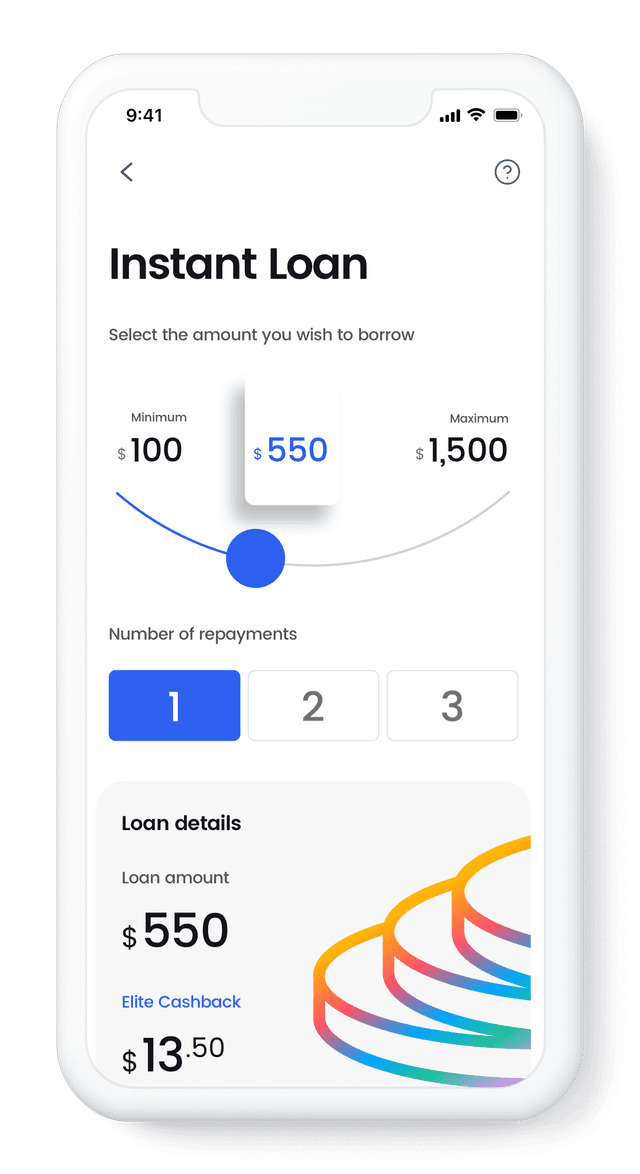
At iCash, the stated cost is $14 per $100 borrowed. For example, a $500 loan has a $70 borrowing cost and a $570 total repayment amount. In Ontario, a $500 loan repaid over 14 days has an APR of 365%; over 62 days, the APR is 82.42%.
4. Does the repayment actually fit?
This may be the most important question.
A loan can solve today's problem and still create another one in the future if the repayment leaves you short for rent, groceries, utilities or other essential expenses.
If you already need to borrow to cover existing loan payments, that's a different situation from needing a one-time bridge for an unexpected expense. Canada's consumer guidance specifically warns that payday loans are expensive and that missed payments can increase the amount you owe.
Run these four questions against any lender, not just iCash.
Is a “No Refusal” Loan Right for You?
A short-term loan may be relevant when you have a specific expense, know where the repayment will come from and can comfortably cover the payment when it is due.
It may be a sign to pause when you're borrowing repeatedly, using one loan to pay another, or regularly running out of money before your next income payment. This is called a debt cycle and is one the most common problems with using a payday loan without considering the repayment cost.
In that situation, borrowing again may not address the underlying cash-flow problem. A credit counsellor can help you look at your budget and debt without requiring you to take another loan.
If you do decide to compare lenders, focus less on the phrase “no refusal” and more on what the lender actually offers: who is licensed, what information is required, how repayment works, what the loan costs and whether the payment fits your budget.