
TL;DR

No refusal payday loans Alberta are not guaranteed loans. Licensed lenders assess applications based on eligibility requirements, including verifiable income and banking information. Alberta payday loans range from $100 to $1,500 and must be repaid over 42 to 62 days through scheduled installments. The maximum cost is $14 per $100 borrowed, with additional rules applying to missed payments.
Being turned down for a loan can be frustrating, especially when you have regular income. If your pay varies from one deposit to the next, you may find yourself searching for no refusal payday loans Alberta.
What’s important to know is that loan applications aren't assessed on earnings alone, and different lenders may have varying eligibility criteria. Understanding what can affect an application and what Alberta's rules allow can help you make sense of your options.
In this guide, we’ll explain why Alberta loan applications might be refused, what the province's payday lending rules allow, how much borrowing can cost, and what options you have if you've already been turned down.
Key Takeaways
“No refusal payday loans Alberta” is a search term, not a guarantee of approval. Lenders review each application to make sure it meets their eligibility requirements.
Alberta payday lending rules require loans to have a 42-to-62-day term with multiple scheduled payments. Borrowers can also repay all or part of the balance early without a prepayment penalty.
Payday loan costs in Alberta are capped at $14 per $100 borrowed, and missed payments can result in additional interest or other penalties, including bank-charged NSF fees.
A refused application doesn't always mean you can't borrow. Reviewing the reason for the decline, correcting application issues and considering alternatives such as free credit counselling can help determine your next step.
Why “no refusal” is searched so heavily in Alberta
For many Albertans, a reliable income doesn't necessarily mean receiving the same amount on every paycheque. Shift work, seasonal employment, contract work and energy-sector jobs can all create deposits that vary in amount or timing. You may have recurring employment and enough income to manage your expenses, but your bank activity may not look as predictable as a traditional salary.
That difference can affect how a lender assesses an application. When income patterns are difficult to verify or don't fit a lender's criteria, an application may be refused even if you have a legitimate, ongoing source of income.
Looking beyond a traditional paycheque
If you've ever searched for a loan that promises approval, you may be wondering whether lenders will consider you if you have bad credit, irregular income, or a history of NSF transactions. In Alberta, lenders can apply their own approval criteria, so an application may be refused even if you have regular income and a bank account.
That doesn't mean you're out of options. There are lenders in Alberta that offer multi-repayment loans for people with varying income patterns or bad credit. Instead of repaying the full borrowed amount at once, these loans spread repayment across multiple payments, giving you more time to manage the balance.
Depending on the lender, installment-based loans may offer:
A straightforward online application process, often available 24/7.
Quick lending decisions, usually within minutes of applying.
Clear information about the loan's total cost before you accept the agreement.
Interac e-Transfer® payments for convenient access to funds.
Multiple repayment dates, which may make payments easier to fit into your budget. Albertans can generally have 2 to 7 repayments, depending on borrowing terms.
Early repayment options, depending on the lender's terms and agreement.
What Alberta's rules actually say about guaranteed approval
If you've been previously refused a loan, it's easy to see why “guaranteed approval” sounds appealing. Alberta's rules put some limits on what payday lenders can say and do. Lenders must have a license to operate in the province, and the Consumer Protection Act includes rules against misleading or false information. The province specifically points payday lenders to section 124.2 of the Act, which covers prohibited practices.
Here's a simple example: if a lender advertises, “Everyone is approved,” but still has to review your application and can refuse it, that statement could give you the wrong impression about what you're actually applying for. A licensed provider can't use advertising to make approval sound certain when approval depends on meeting its requirements.
That's why there's an important difference between a lender that considers different income situations and one that promises guaranteed approval. The first may be possible; the second shouldn't be presented as a certainty.
You can read more about Alberta's payday lending rules through the province'sConsumer Protection Act and related regulations. For a closer look at “no refusal” claims, see our guide to no refusal payday loans Canada.
Five reasons an Alberta loan application gets refused
A refused application doesn't necessarily mean you can't qualify for a loan. Lenders consider several factors when reviewing a loan application, including your income, banking history and existing financial commitments.
Here are five common reasons you may be declined in Alberta, plus what you can do to address each one:
1. Your earnings are difficult to verify. Irregular deposits or changing pay amounts can make income verification more difficult, particularly if your employment or payment schedule varies.
Fix: Have recent pay stubs, bank statements or other accepted proof of income ready when you apply.
2. Your banking history raises concerns. Frequent NSF transactions, returned payments or other issues in your bank account may affect how a lender reviews your request.
Fix: Review your recent banking activity and, where possible, address recurring NSF activity before submitting a new application.
3. You already have several loan obligations. A payday loan in Alberta can involve multiple scheduled repayments, depending on the agreement. If you're already managing other loans or payments, those existing commitments may affect your application.
Fix: Review your current loan obligations and budget before taking on another repayment.
4. You're applying through a lender that isn't licensed in Alberta. Alberta requires payday lenders, including online lenders, to hold a Payday Loan license. Applying through an unlicensed provider can create consumer-protection concerns rather than improve your chances of approval.
Fix: Check that the lender is licensed in Alberta before submitting an application.
5. Your application details don't match. Missing information or inconsistent details can delay the process or prevent a lender from verifying your information.
Fix: Double-check your personal, employment, income and banking details before submitting your application.
What you can borrow in Alberta and what it costs
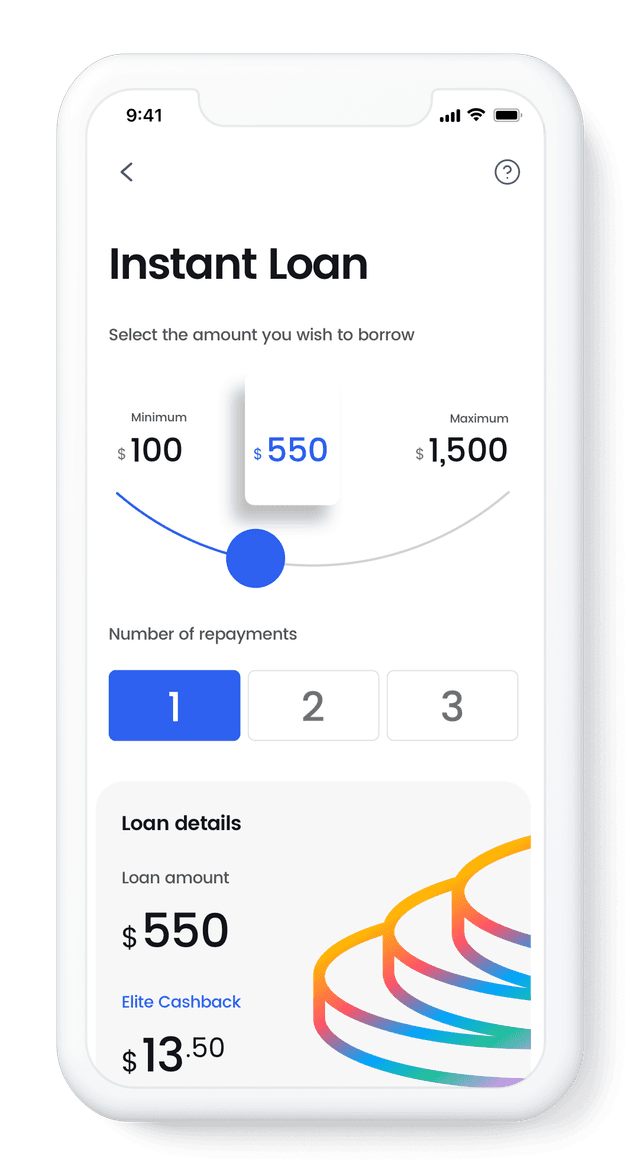
You can borrow between $100 and $1,500 through a short-term loan. The maximum cost of borrowing is $14 per $100 borrowed. For example, borrowing $500 would have a $70 borrowing cost, for a total repayment of $570.
Amount Borrowed | Cost of Borrowing | Total Repayment |
$100 | $14 | $114 |
$500 | $70 | $570 |
$1,500 | $210 | $1,710 |
A $100 loan over 62 days has an 82.42% APR. Your repayment schedule can range from 2 to 7 payments, depending on your income frequency.
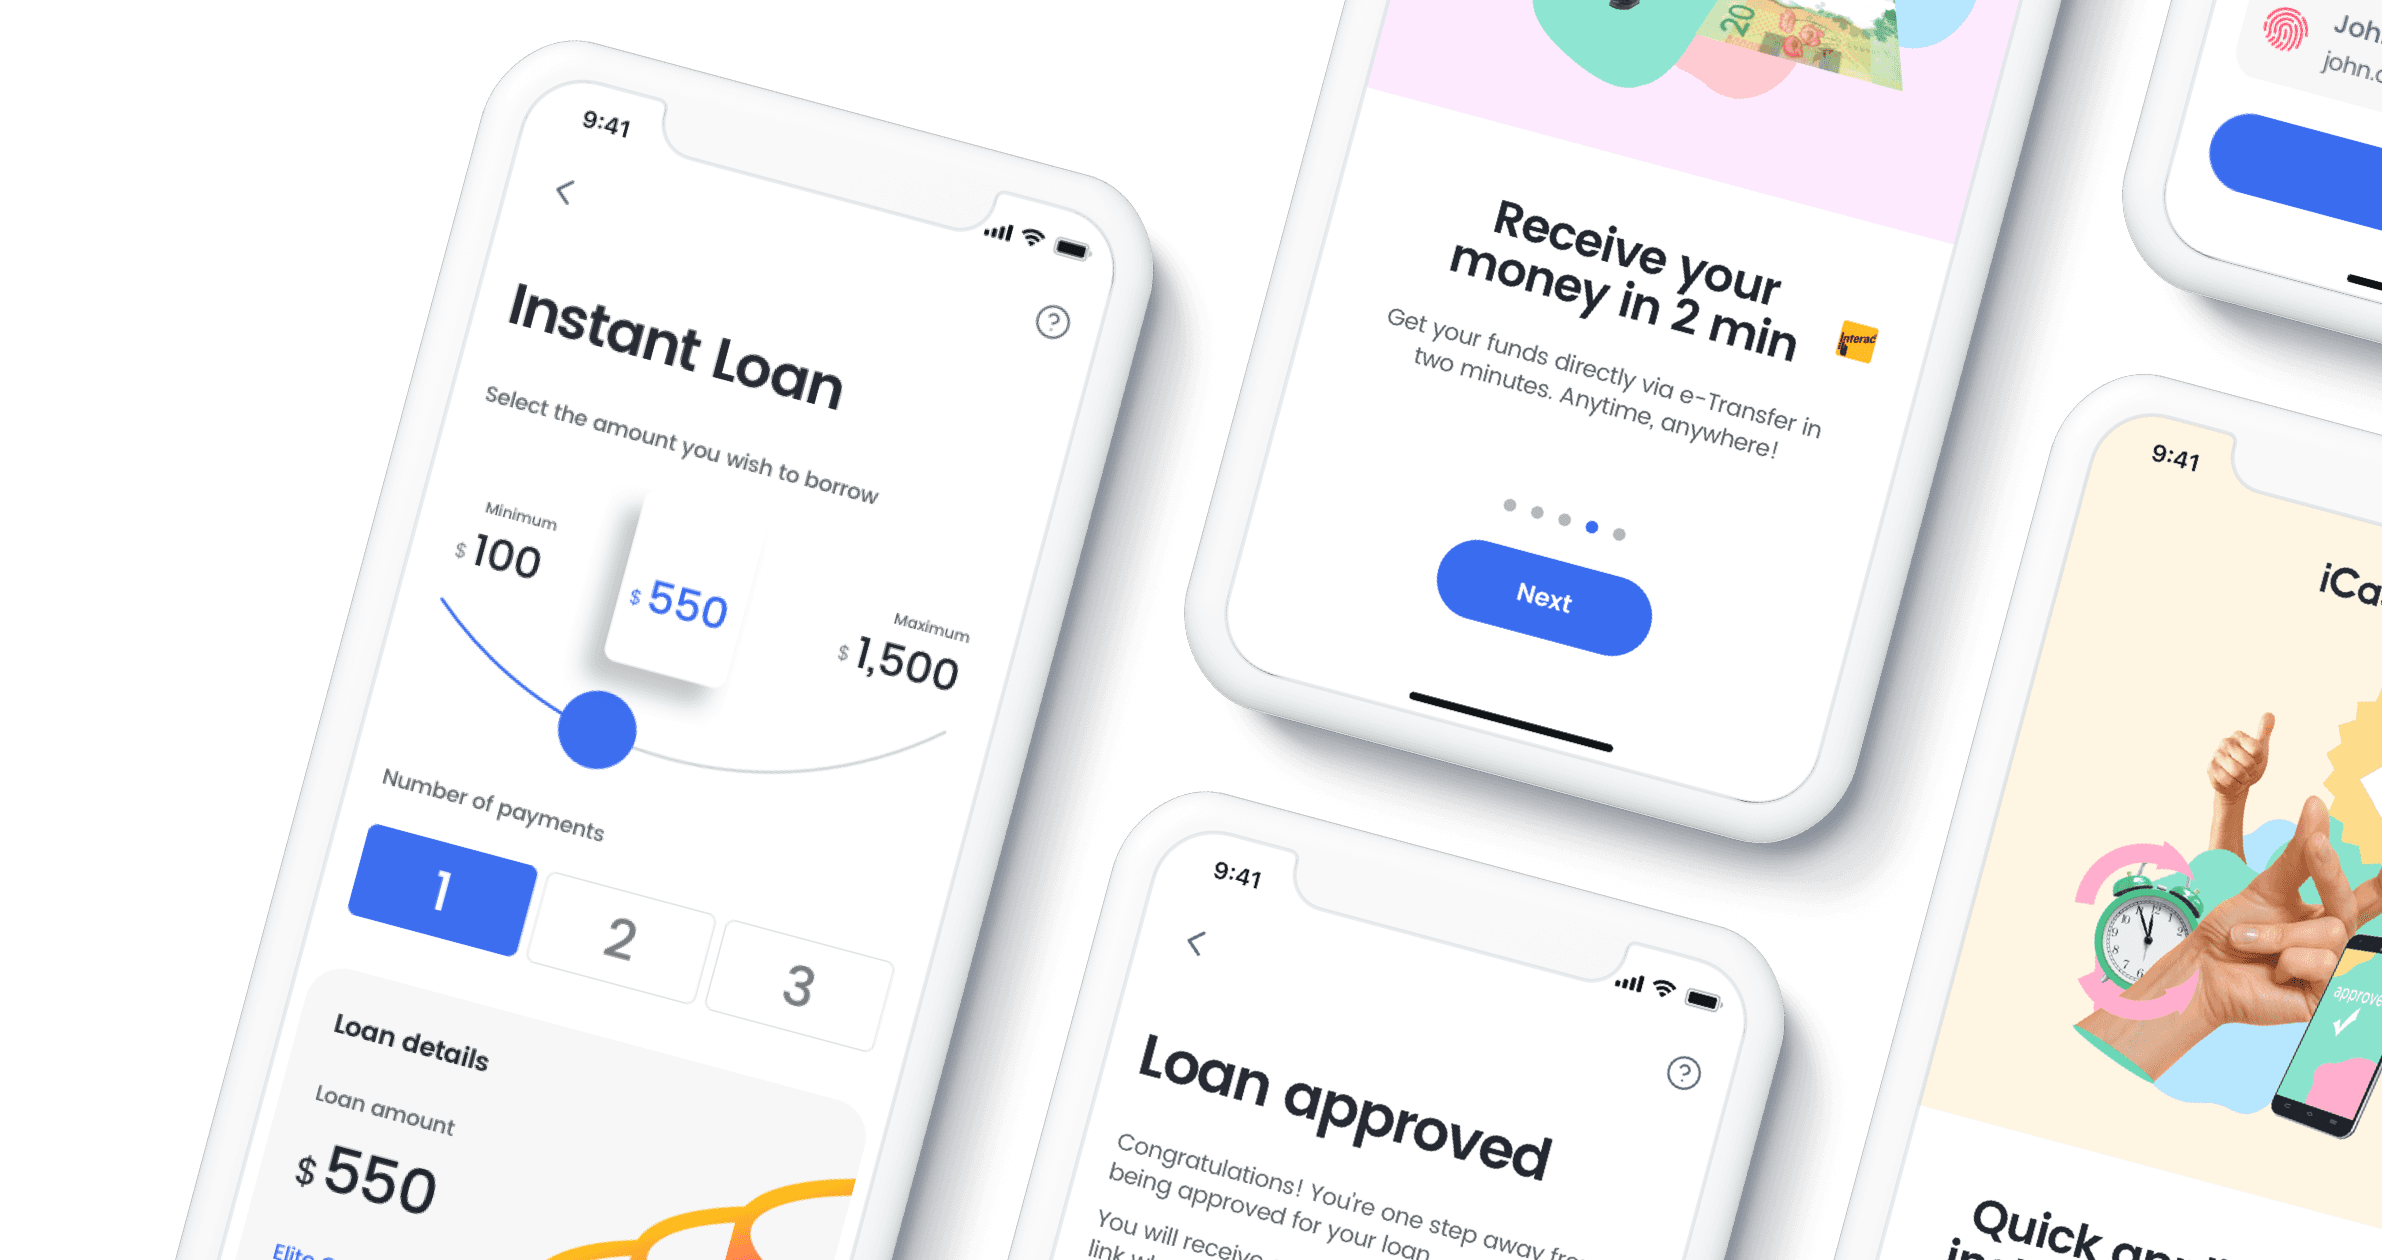
Once approved, funds can be sent by Interac e-Transfer, typically within 2 minutes. Learn more about getting a loan via Interac e-Transfer. Funding is available 24/7, including weekends and holidays.
Who qualifies in Alberta
Qualifying for a short-term loan in Alberta isn't limited to people with a traditional 9-to-5 job. Lenders may consider recurring income from different sources, as long as the income can be verified and the applicant meets the lender's eligibility requirements.
Generally, you'll need to:
Be at least the age of majority in Alberta.
Be an Alberta resident.
Have a verifiable, recurring source of income.
Have an active Canadian bank account.
iCash is an online lender operated by Finabanx Ltd. and is licensed to provide payday loans in Alberta under licence #341941. You can also verify a lender's licence through Service Alberta and Red Tape Reduction's business licence search.
Your income doesn't necessarily have to look the same from one paycheque to the next. Shift work, seasonal employment, contract work and other income sources may still qualify if the lender can verify your income and assess your ability to repay the loan.
For iCash, your first application includes a credit check, while returning customers don't need another credit check. Other eligibility requirements still apply, and meeting the requirements does not guarantee approval.
How Alberta's 42-to-62 day rule changes your repayment
In Alberta, payday loans have terms of 42 to 62 days and use scheduled installment payments. The number and timing of payments depend on the borrower's income frequency.
That can matter if you don't get paid every two weeks. For example, someone with a biweekly paycheque may make repayments around regular paydays, while a seasonal worker with a different income schedule may have payments timed around when they receive their income.
Here is an example of how a repayment schedule could look:
Pay Schedule | Example Repayment Schedule for Alberta Residents |
Every 2 weeks | Payment 1 → Payment 2 → Payment 3 → Payment 4 |
More frequent income | Payment 1 → Payment 2 → Payment 3 → Payment 4 → Payment 5 → Payment 6 |
Monthly or less frequent income | Payments may be scheduled around the borrower's income dates |
A seasonal worker or someone who doesn't receive a biweekly paycheque may have a different repayment schedule based on their income timing. The exact number and timing of payments depend on the loan agreement.
Alberta Payday Loan Repayment Rules
The province sets specific rules for how payday loans must be repaid:
Scheduled payments: Lasting between 42 and 62 days. The repayment schedule must also cover multiple pay periods based on how frequently you receive payments.
Early repayment: You can pay all or part of your outstanding balance before the scheduled payments are finished.
No prepayment penalty: A lender cannot charge you a prepayment fee or penalty for paying your balance early.
So, while your loan starts with a scheduled installment plan, you can still pay it off sooner if you have the money available.
What it costs if you repay late in Alberta
Under Alberta payday lending rules, missing a scheduled payment can add costs to your loan. If a payment doesn't go through because you don't have enough money in your account, the lender may charge a dishonoured payment fee of up to $20. You may also be charged interest of up to 2.5% per month on the outstanding balance. Alberta's rules do not allow that interest to compound.
Your bank may also charge an NSF fee when a payment doesn't go through because of insufficient funds. The Financial Consumer Agency of Canada says federally regulated banks cannot charge more than $10 for an NSF fee on a personal deposit account, subject to the applicable federal rules.
A missed installment does not erase the remaining balance. The amount still owing remains due, and additional permitted interest can apply until the loan is repaid. Understanding the fees before you borrow is an important part of responsible loan use.
What to do if you've already been refused in Alberta
Start by finding out why your application was declined, then fix any issues you can, such as missing information, unverifiable income or recent NSF activity. Check your credit report for errors and review your existing debts before applying again. You may also want to look at options such as bad credit loans in Alberta, which are built around exactly this situation.
There isn't a set waiting period that guarantees approval. Instead, wait until you've addressed the reason for the declined application and can comfortably manage another repayment.
If you're searching for no refusal payday loans in Alberta or payday loans in Alberta with no credit check after being turned down, know that reputable lenders cannot guarantee approval or skip credit checks entirely. Short-term lending still has eligibility requirements and should always be repaid on time.
And sometimes, another loan isn't the right answer. Free credit counseling can help you review your debts and explore other options.