
The main difference between installment loans and payday loans is how you repay them. A payday loan is generally repaid in one lump sum on a set date, while an installment loan divides the repayment into two or more scheduled payments over a longer period.
Both can provide short-term access to funds, but the repayment structure can make one a better fit for your budget than the other. Understanding the difference between a payday loan and an installment loan can help you choose based on what you can comfortably repay.
Key Takeaways

Payday loans are usually repaid in one lump sum, while installment loans use two or more scheduled payments.
iCash offers both payday and installment loan options; availability is based on provincial regulations.
Both loan types can cost $14 per $100 borrowed through iCash; the main difference is how repayment is structured.
Both can be available for up to $1,500, depending on your eligibility and provincial rules.
The right option depends on what you can comfortably repay and which payment schedule fits your budget.
Key Differences: Repayment, Cost, Loan Amounts, and Eligibility
The main difference between installment loans and payday loans is how you repay the money.
A payday loan is generally repaid in one lump sum on the agreed due date, while an installment loan (sometimes called a personal loan) spreads the repayment across multiple scheduled payments. This can make installment payments easier to fit into a budget, while a payday loan may be simpler when you can comfortably repay the full amount with your next paycheque.
With iCash, both loan structures use a $14-per-$100 borrowing fee, so the repayment structure—not the fee rate—is the main difference. Both products also use income and ability to repay as part of the qualification process. This means your credit score isn't the only factor considered, which may be helpful if you've had difficulty qualifying for traditional credit based primarily on your credit profile.
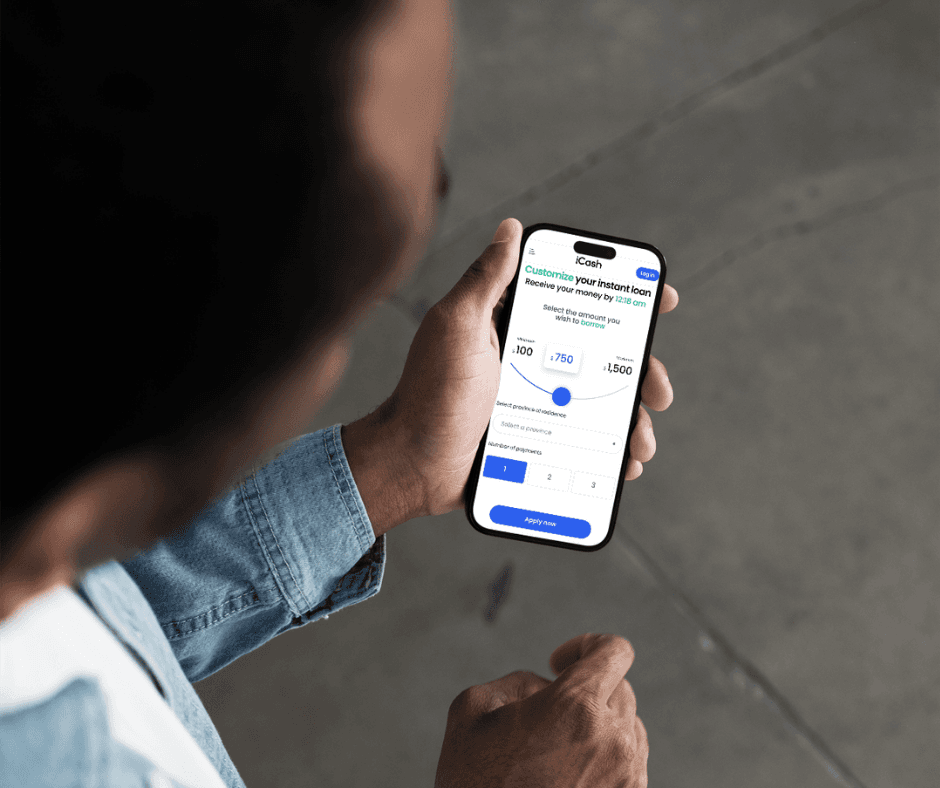
iCash may offer installment repayment depending on your province and circumstances, giving eligible borrowers the option to spread their repayment across multiple scheduled payments. The application and funding process is also designed to be fast, with approved funds typically sent by Interac e-Transfer® in about two minutes.
For example, a $500 payday loan under single-payment terms would have a $70 borrowing fee, for a total repayment of $570. If the same $500 loan is structured as an installment loan over three payments, the total borrowing cost can still be $70, but the $570 repayment is divided across the scheduled payments according to the loan agreement.
The exact number and timing of personal loan payments depend on your province, income frequency, and applicable loan terms. So when comparing an installment loan vs. a payday loan, focus less on the total fee and more on which repayment schedule you can comfortably manage.
Where iCash Offers Installment Loans by Province
Installment repayment funding depends on provincial regulations and the terms available through iCash. Because these rules, requirements, and product terms can change, check the applicable provincial information before applying.
Province | Repayment Structure | Notes |
Alberta | Installment repayment available | Terms can range from 42 to 62 days, with payments depending on income frequency. |
Ontario | Primarily single repayment | A third loan within 63 days may be eligible for installment repayment under applicable rules. |
Nova Scotia | Single repayment | Installment repayment isn't currently available under provincial payday-lending rules. |
British Columbia | Varies | Check current iCash terms for available payment options. |
Manitoba | Varies | Check current iCash terms for available payment options. |
New Brunswick | Varies | Check current iCash terms for available payment options. |
Prince Edward Island | Varies | Check current iCash terms for available payment options. |
For Alberta borrowers, you can learn more about payday loan terms in Alberta. Information for borrowers in British Columbia, Manitoba, New Brunswick, and Prince Edward Island is also available.
Pros and Cons of Installment Loans
Installment loans can make a short-term expense easier to fit into your budget because repayment is divided across multiple payments rather than coming from one paycheque.
Pros:
Smaller scheduled payments can be easier to budget around.
Predictable repayment dates make it easier to plan ahead.
Spreading repayments can reduce the impact on a single paycheque.
A fixed schedule gives you a clear path to paying off the loan.
Cons:
The loan remains an obligation for longer and lenders determin your interest rate based on credit score.
You need to keep enough room in your budget for each scheduled payment.
Installment repayment isn't available in every province.
Taking on another payment while already managing debt can put additional pressure on your budget.
An installment structure can make sense when you have enough income to cover each scheduled payment but would find one large repayment difficult to manage.
Pros and Cons of Payday Loans
A payday loan can be a straightforward option when you have an unexpected one-time expense and can comfortably repay the full amount on the due date.
Pros:
One repayment can resolve the loan without an ongoing payment schedule.
The repayment date is clear from the start.
It can suit a one-time financial gap that you know you can cover with your next paycheque.
Cons:
The full repayment takes a larger portion from one paycheque.
Repeatedly taking out new payday loans can make it harder to manage your finances.
Payday loans are generally more expensive than many traditional forms of credit.
A payday loan may work better when you need to cover a temporary gap and can comfortably afford the full repayment by the due date.
Which Is Better for Your Situation and Credit Profile?
Neither loan type is automatically better for everyone. Your budget, rate repayment ability. and timing should drive the decision more than your credit profile.
A payday loan may be the simpler fit if you have a one-time emergency and know you can repay the full amount by your next paycheque. You resolve the loan in one payment rather than carrying another payment into future pay periods.
An installment loan may be a better fit if you have a short-term cash gap but would prefer to divide repayment to your lender across a couple of pay periods. Smaller scheduled payments may be easier to work into your budget.
Your credit history doesn't necessarily make one structure more suitable than the other. iCash considers income and ability to repay when reviewing applications for both loan types.
If you're deciding between a payday loan or installment loan, start with one question: Which repayment schedule can you comfortably manage?
Risks and Potential Pitfalls to Watch For
The main risk with either type of short-term loan is taking on a payment you can't comfortably afford. A loan can help with a one-time gap, but it can become harder to manage if borrowing becomes part of your regular monthly budget.
With a payday loan, repeatedly taking out another loan instead of repaying the existing balance can increase your borrowing costs and leave you relying on short-term credit. This can lead to a debt cycle where interest keeps increasing, and you end up owing more than you can pay.
With an installment loan, the smaller payments may feel easier to manage, but the obligation continues across multiple pay periods.
Before borrowing, consider whether you're dealing with a one-time expense or an ongoing income shortfall. If the same expenses keep coming up each month, another payday or installment loan may not address the underlying problem.
It's also important to understand the consequences of missing a scheduled payment or failing to repay the loan on time. Review your agreement carefully and contact the lender if you're concerned about making a payment.
Tips for Smart, Responsible Borrowing
Before accepting or applying for any type of loan, responsible borrowing means understanding your options and the cost of each.
Look into lower-cost borrowing options like a line of credit, a loan from family or friends, a credit card, or using savings. Learn about the interest rates typically charged so you understand how much borrowing money will cost.
If you have checked these funding options and they are not available, a payday or installment loan may help.
A few simple checks can help you decide whether either loan type fits your situation:
Borrow only what you need. Don't borrow the maximum just because you qualify.
Know the repayment details. Confirm the exact amount, payment dates, and total cost before signing the agreement.
Don't use a new loan to repay an old one. If you regularly need another loan to cover an existing payment, consider other forms of financial assistance.
Confirm the costs. Look at the total cost, fees, and repayment schedule before deciding which type of borrowing fits your budget.
Borrowing responsibly will help you avoid going into debt and increasing your financial burden. Paying off debt, especially debt with higher interest rates, can strain your budget. Many who fall into the debt cycle struggle to recover for years. Understanding the rates, costs, and requirements of borrowing will help you avoid this.
Before applying for any loan or funding option, calculate the loan cost.
Because provincial regulations can change, confirm the current repayment structure and terms available with the lender you are considering before accepting a loan.
How to Apply — 3 Steps
If you've decided that one of these loan types fits your situation, the application process is straightforward:
Apply online. Choose the loan type that fits your needs and complete the application.
Receive an instant decision. We review your information based on factors such as income and ability to repay.
Receive your funds. If approved, funds can typically be sent by Interac e-Transfer within about two minutes after you sign the agreement.
The funding process is available 24/7, although your bank may require additional processing time.
You can learn more about instant loan decisions or how payday loans are received by Interac e-Transfer.