
Many people receiving ODSP worry they'll be turned down simply because they receive disability benefits instead of employment income. After being declined by a bank or seeing confusing eligibility requirements elsewhere, it's easy to wonder whether anyone will approve your application.
The truth is more encouraging than many people realize. While no licensed lender in Canada can legally promise "no refusal" or guaranteed approval, ODSP is recognized as a valid source of income by many licensed payday lenders. The key is understanding what lenders actually look for, and avoiding misleading claims that sound too good to be true.
Key Takeaway

ODSP is accepted as qualifying income by iCash and many licensed Ontario lenders
No licensed lender in Canada can promise approval before reviewing your application
Lenders look for regular ODSP deposits in an active bank account, not a T4
A payday loan may affect your ODSP if it is not used for an ODSP-approved purpose
ODSP pays on the last business day of the month, which shapes your repayment date
Does ODSP count as income for a payday loan?
Yes. ODSP is accepted as qualifying income by iCash and by many licensed Ontario payday lenders. Your income does not need to come from an employer. What matters is that the deposits are regular, verifiable in your bank account, and large enough to cover repayment alongside your essentials.
The Ontario Disability Support Program (ODSP) is administered by Ontario's Ministry of Children, Community and Social Services. It pays a fixed amount on a fixed monthly schedule. For a lender assessing whether you can repay, that predictability is an advantage, not a disadvantage.
Banks tend to weight employment income heavily. That is why so many ODSP recipients get declined at a bank and assume every lender works the same way. Licensed payday lenders assess applications differently.
What Does "No Refusal" Actually Mean?
"No refusal payday loan" is a marketing phrase, not a legal or regulated lending product.
In Canada, every licensed lender must review an application before approving a loan. That means no company can honestly guarantee approval before verifying that an applicant meets the basic eligibility requirements.
When you see phrases like "no refusal," they usually mean one of two things:
The lender has a high approval rate for applicants who meet its requirements.
The lender focuses more on stable income than on traditional employment.
That's very different from promising that everyone will be approved. A reputable lender will always explain how applications are assessed, what fees apply, and what you'll repay before you accept a loan.
What Ontario lenders actually check when your income is ODSP
Licensed lenders verify a short list of basics rather than building a full financial profile. For ODSP recipients, the checks are straightforward.
A lender will typically confirm that you:
Are at least 18, the age of majority in Ontario
Live in Ontario and hold an active Canadian bank account in good standing
Receive regular ODSP income support
Have recent ODSP deposits visible in that account
That last point is the one that trips people up. Some recipients get ODSP on a reloadable payment card instead of by direct deposit. A lender cannot see the deposit history it needs in that case. Switching to direct deposit is usually the fastest way to fix a declined application.
What lenders are not looking for
You do not need a T4, an employer reference, or proof of full-time work. Receiving ODSP does not disqualify you. You also do not need to be off ODSP or working part-time to apply.
ODSP and Ontario Works are treated the same way
Both are Ontario social assistance programs, and both are accepted as qualifying income at iCash. If you are receiving Ontario Works payments while your ODSP disability adjudication is still in progress, you can still apply.
How ODSP payment timing affects your repayment
ODSP income support is paid on the last business day of each month. When that date falls on a weekend or holiday, the payment moves to the business day before. You can check the full schedule on our ODSP payment dates page.
That single monthly deposit changes how a short-term loan works for you. In Ontario, an iCash loan is repaid in one payment, except on a third loan within 63 days. So your repayment date is set against your next ODSP deposit, not a biweekly paycheque.
Two practical consequences:
If you borrow just after your ODSP deposit lands, your repayment window is close to a full month
If you borrow a few days before your deposit, repayment arrives quickly
Before you apply, run the numbers with the loan budgeting calculator so you know the exact repayment amount and date.
What an iCash loan costs an Ontario borrower
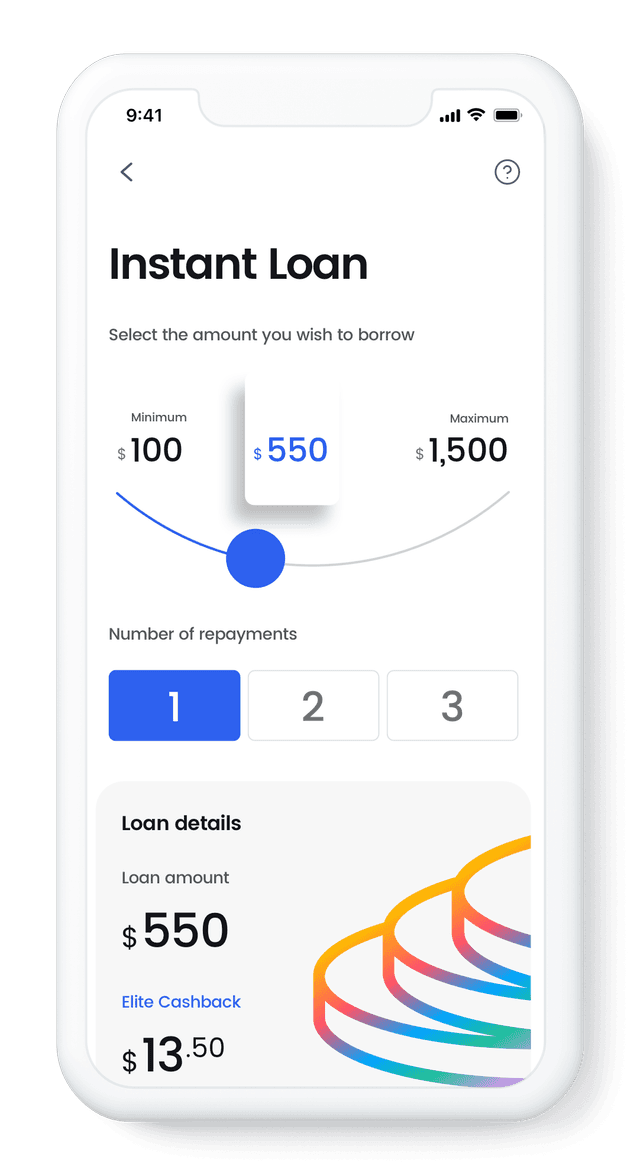
iCash charges $14 per $100 borrowed. There are no separate application or e-Transfer fees.
For an Ontario borrower taking $500 for 14 days:
Amount borrowed | Cost of borrowing | Total repayment | APR |
$500 | $70 | $570 | 365% |
That APR looks alarming, so here is what it actually describes. APR is the annualized cost, and a payday loan is not held for a year. The same $70 fee spread over 62 days works out to an APR of about 82.42%. The dollar cost does not change; only the time period used to express it does.
iCash is licensed in Ontario under licence #4733142 and operates in seven provinces. iCash is a member of the Canadian Consumer Finance Association and holds a 4.7 rating on Trustpilot.
On credit checks: a credit check is only carried out on your first loan application. Every loan after that is exempt from one.
Applications are open 24/7 and approved loans are sent by Interac e-Transfer, typically within about 2 minutes. iCash only offers one loan at a time. Approval is not guaranteed and conditions apply.
Warning signs when a site promises guaranteed ODSP approval
Sites targeting disability benefit recipients with promises of automatic approval are worth treating with caution. Slow down before you enter your banking details.
Watch for:
Claims that everyone is approved regardless of circumstances
Any request for an upfront fee before a loan is advanced
No provincial licence number displayed anywhere on the site
A claim to represent a government ODSP loan program, which does not exist
Pressure to accept before the total repayment amount is shown
Payday lending is licensed provincially in Ontario. More on how to spot a fraudulent lender is on our guide to warning signs of lending scams.

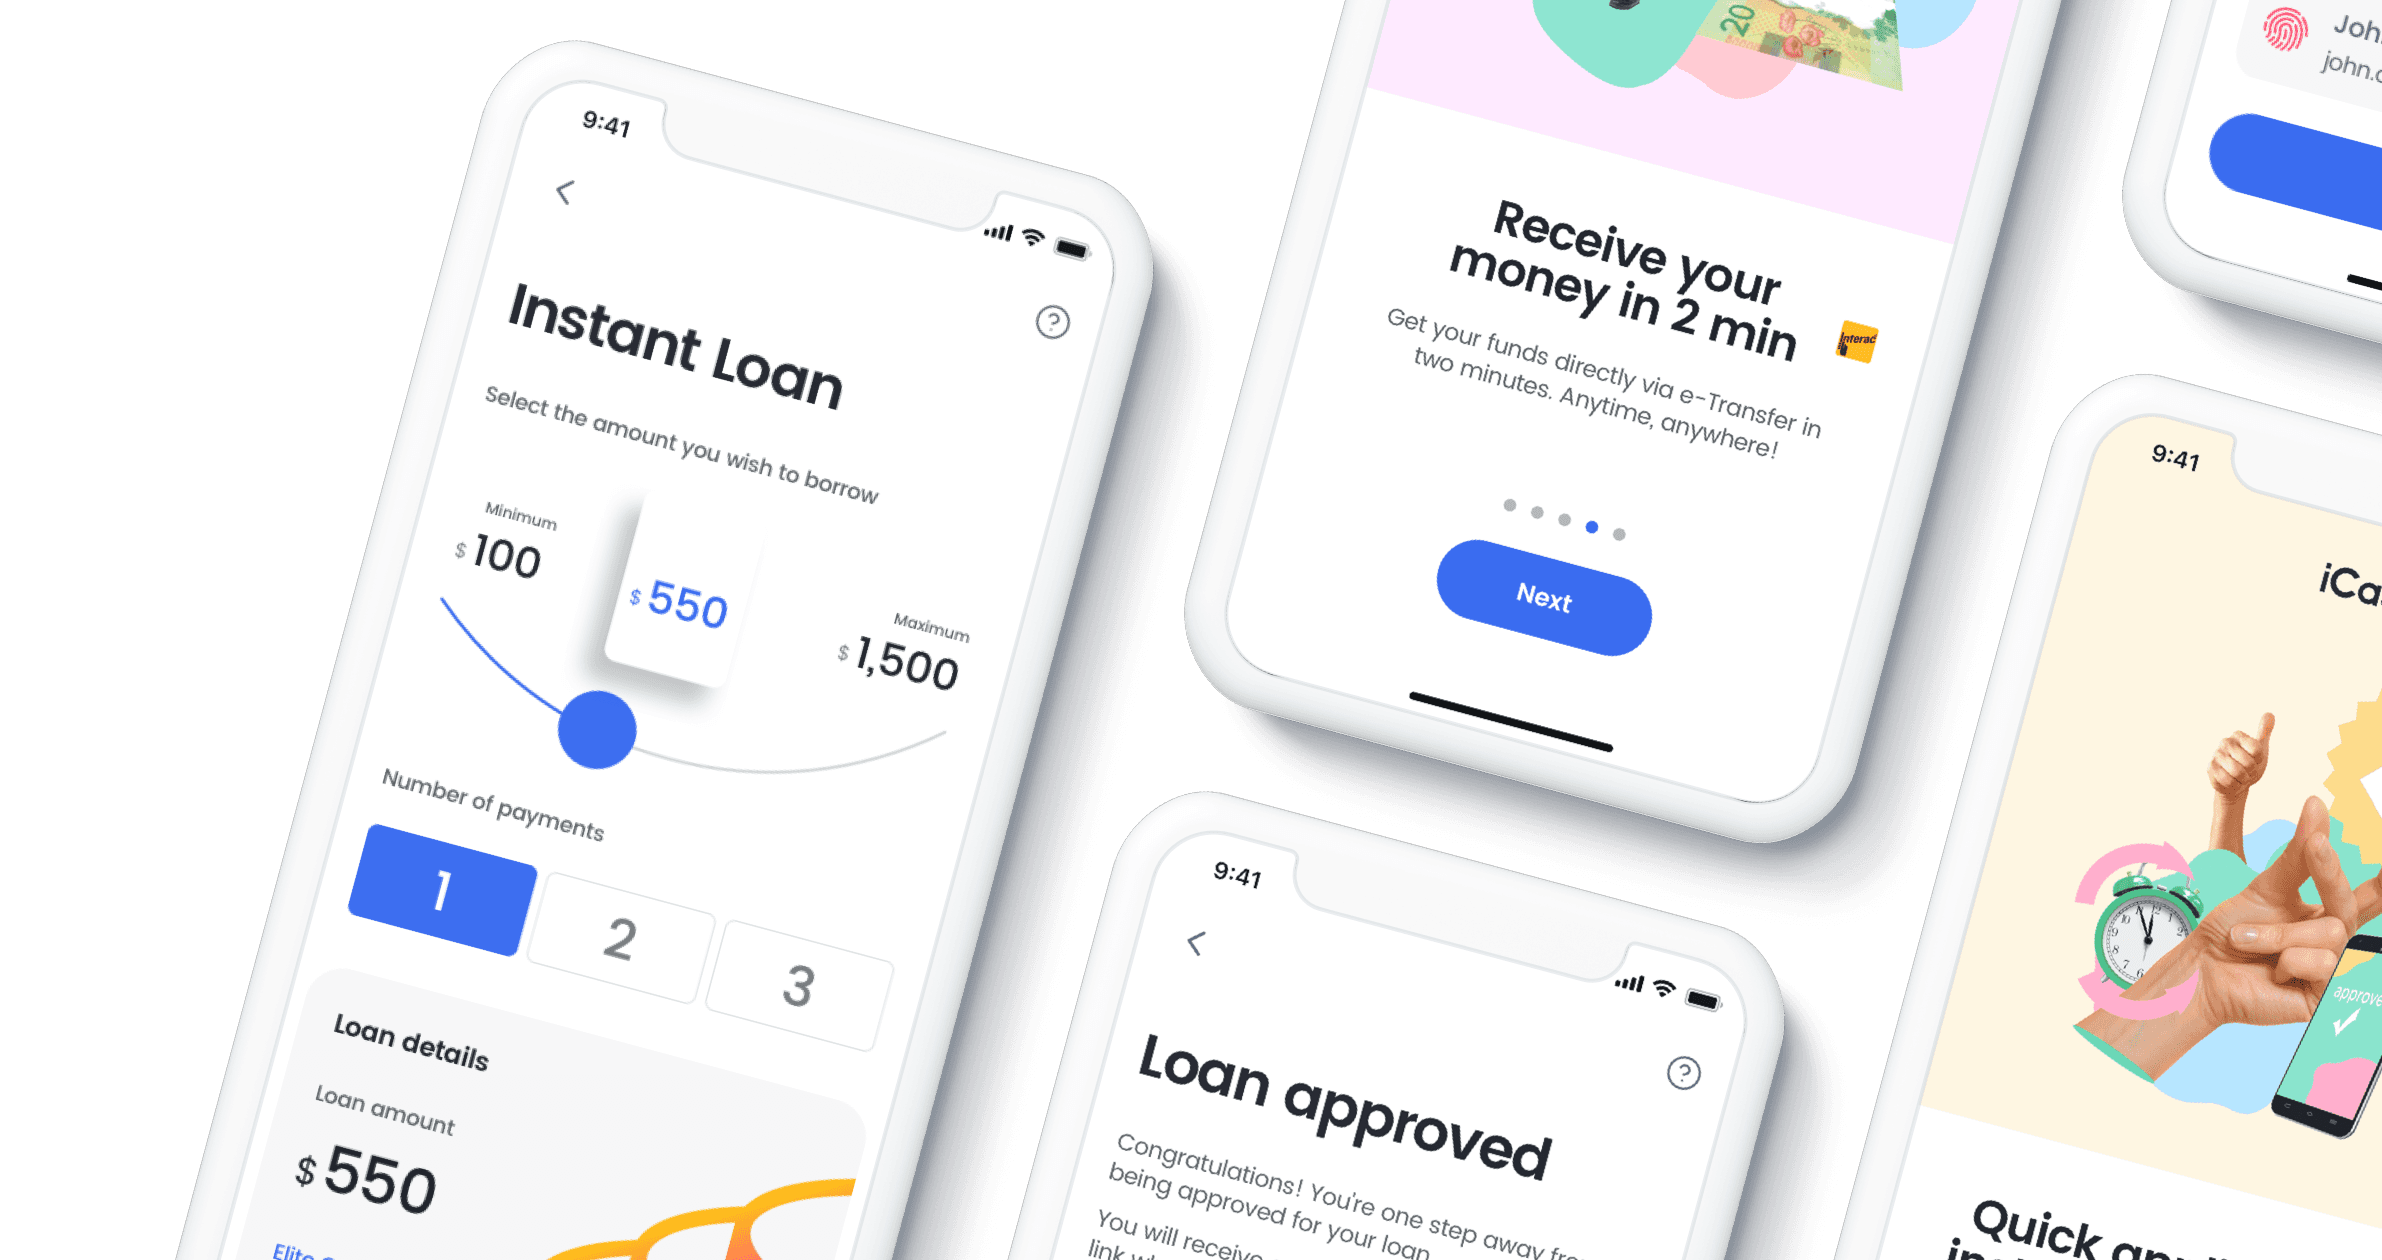
How to apply in 3 steps
1. Complete the online application. Enter your personal details, your ODSP income, and your banking information.
2. Get an instant decision. Your application is reviewed against straightforward eligibility criteria, and you will know the outcome right away.
3. Receive your funds. Once you sign your agreement, funds are sent by Interac e-Transfer, typically within about 2 minutes, 24/7.
Borrow Responsibly
A short-term loan should help you solve an immediate problem, not create a bigger one later. Before you apply, make sure you can repay the loan on time while still covering essentials like rent, groceries, utilities, and transportation.
If you're unsure whether a loan fits your budget, take a few minutes to review your income and upcoming expenses first. iCash also provides resources on borrowing responsibly so you can make an informed decision before taking on any loan.
If you'd like to understand your repayment before applying, use the loan calculator to estimate the total borrowing cost.
Frequently Asked Questions
Can I get a payday loan on ODSP with no credit check?
Licensed lenders do not offer true "no credit check" payday loans. iCash uses a simple one-time verification as part of the application process, but approval is based primarily on your overall eligibility rather than employment status alone.
Does iCash approve ODSP applicants?
Yes. ODSP is accepted as qualifying income, and many recipients are approved when they meet the eligibility requirements. Approval is not guaranteed, and conditions apply.
What happens if I get declined? Can I reapply?
Yes. If your circumstances change or you're able to address the reason your application wasn't approved, you can apply again in the future.
Will a payday loan affect my ODSP benefits?
No. An iCash loan is a private borrowing arrangement and is not reported to your ODSP caseworker as part of the application process. If you have questions about your personal situation, it's always a good idea to review current ODSP rules or speak with your caseworker.
Final Thoughts
Searching for "no refusal payday loans" usually isn't about expecting guaranteed approval. It's about wanting a fair chance.
The good news is that receiving ODSP does not prevent you from qualifying for a payday loan. Licensed lenders understand that disability benefits provide regular monthly income, and many assess applications based on financial stability rather than employment alone.
The most important step is choosing a lender that is transparent about its costs, follows provincial regulations, and explains its approval process honestly—without making promises that no licensed lender can legally keep.