Menu
Date Published: October 28, 2026
Table of contents :
In Canada, a home renovation loan is a category that covers several products. The right one depends almost entirely on your project size and whether you have home equity.
This guide compares a home equity line of credit (HELOC), a mortgage refinance, CMHC purchase-plus-improvements, personal loans, contractor financing, charge cards, government energy programs, and short-term loans for small, urgent costs.
Quick Answer

Paying for a home renovation can involve several types of financing. If you have at least 20% equity, a HELOC or mortgage refinance will often be among the lower-cost choices. If you don’t have enough value in your home, you may qualify for an unsecured personal financing based on your credit and finances. For smaller jobs, credit cards and contractor promotions can be convenient when you have a clear plan to repay the balance quickly. Short-term finance is better kept for urgent, relatively small repairs rather than larger renovations you can plan for in advance.
It's any borrowing you use to pay for work on your home. Canadian lenders rarely sell a product with that exact name, so treat it as an umbrella term. Every choice falls into one of two groups:
Secured borrowing. Your home backs the loan (HELOC or refinance). Rates are lower, and limits are higher, but the lender can claim the property if you stop paying.
Unsecured borrowing. Only your credit and income back the loan (personal funding, short-term loans). Rates are higher, and large amounts are harder to get.
That split decides how much you can borrow, what it costs, and how long approval takes.
Most Canadian renovations cost between a few hundred dollars and $75,000. These ranges come from HomeStars cost guides, which were last updated in August 2026, and each project links to its source.
Project | Typical cost range | Likely financing fit |
Small kitchens start at $6,500; large kitchen renovations can exceed $78,000 | HELOC, refinance | |
$8,500 to $21,000 | HELOC, personal loan | |
$10,000 to $65,000 (varies depending on city) | HELOC, refinance, CMHC Improvement | |
$5,000 to $15,000 | HELOC, personal loan | |
Window replacement (10 windows) | $3,900 to $9,200 | Personal funding, HELOC, rebates |
$4,000 to $6,750 | Personal loan, HELOC, rebates | |
$1,963 to $5,806 | Savings, personal loan | |
Deck: $8,000 to $20,000; fence: $2,500 to $10,000 | Personal loan, HELOC | |
Painting (per room) | $200 to $1,800 | Savings, credit card paid in full |
Appliance replacement (per unit) | About $500 to $3,000 | Savings, credit card, short-term loan if urgent |
Prices vary by city and materials. Get three written quotes, and follow CMHC's advice to set money aside for surprises.
Two questions decide the right option: how much do you need, and do you have home equity? Below, we break down the main choices, from the largest typical amount to the smallest.
Option | Typical amount | Typical cost | Speed to funds | Credit requirement | Best for |
HELOC | Up to 65% of home value | Variable, prime plus a margin | 2 to 6 weeks | Good credit, 20%+ equity | Large or phased projects |
Refinance or purchase-plus-improvements | Up to 80% of value; 95% of as-improved value (CMHC) | Mortgage rates plus fees | 3 to 8 weeks | Mortgage qualification | Major renovations, fixer-uppers |
Personal loan | $1,000 to $50,000 | About 7% to 35% APR | 1 to 7 days | Fair to excellent credit | Mid-size projects without equity |
Contractor or retailer financing | Cost of the job | 0% promo, then often 20%+ | Same day | Varies | Balances cleared within the promo |
Credit card | Available limit | Often 20%+ | Instant | Existing | Small jobs paid off fast |
Government programs | Rebates up to $12,000 (Ontario) | Free or low-interest | Weeks to months | Program rules | Energy upgrades |
Short-term loan (iCash) | Up to $1,500 | $14 per $100 borrowed | Minutes | Income-based | Small, urgent costs |
How it works: A reusable line of credit secured by your home.
Typical amount: Up to 65% of your home's value, and 80% combined with your mortgage, according to the Financial Consumer Agency of Canada. You'll need at least 20% equity.
Typical cost: Usually a variable rate based on prime, which means your payments can increase when borrowing expenses go up.
Who it suits: Homeowners with enough equity and good credit who are comfortable using their home as collateral.
How it works: A refinance replaces your mortgage with a larger one. With CMHC Improvement funding, buyers can add renovation expenses to their purchase mortgage right after closing.
Typical amount: Up to 80% of your home's value for a refinance. CMHC Improvement allows up to 95% of the as-improved value on owner-occupied one- or two-unit homes under $1.5 million.
Typical cost: Mortgage rates (usually the lowest available), plus legal and appraisal fees. Breaking a mortgage mid-term can trigger a penalty.
Who it suits: Large projects and fixer-upper buyers. Funds are often released as work is completed.
How it works: A lump sum repaid in fixed payments, which tend to range from one to five years.
Typical total: About $1,000 to $50,000.
Typical cost: It depends on your credit, up to the federal criminal interest rate cap of 35% APR.
Who it suits: Borrowers without equity. Approval leans heavily on score. Compare our loan and line of credit options.
How it works: Instead of arranging funding separately, you apply through a third-party lender the contractor offers. This option commonly includes a 0% promotional period.
Typical total: Usually tied to the project cost.
Typical cost: You may pay no interest during the introductory period, but the rate can climb to 20% or more afterward. Some offers also apply deferred interest from day one if you don’t repay the entire balance before the deadline.
Who it suits: Homeowners who know they can repay the full amount within the interest-free period.
How it works and amount: You pay with your card, up to your available limit.
Typical cost: Card rates can exceed 18%. Many contractors add a card surcharge (Quebec's consumer protection law bans them).
Who it suits: Small jobs paid off within a month or two.
How it works: Rebates and retrofit financing offers are available through some government and utility programs to help pay for energy-saving home improvements.
Typical total and cost: The amount you can receive varies based on the program and type of upgrade. Rebates are yours to keep, while some funding programs charge a reduced interest rate.
Who it suits: Homeowners planning upgrades such as insulation, windows, or a heat pump. Many programs require you to apply and receive approval before starting.
Home renovation loans in Ontario: Ontario homeowners have the same lending options as other Canadians, plus the Home Renovation Savings Program. It offers up to $7,500 for a cold-climate air source heat pump, up to $12,000 for a ground source heat pump, up to $7,700 for insulation, and $100 per window or door opening. Pair a rebate with a HELOC or individual loan to borrow less.
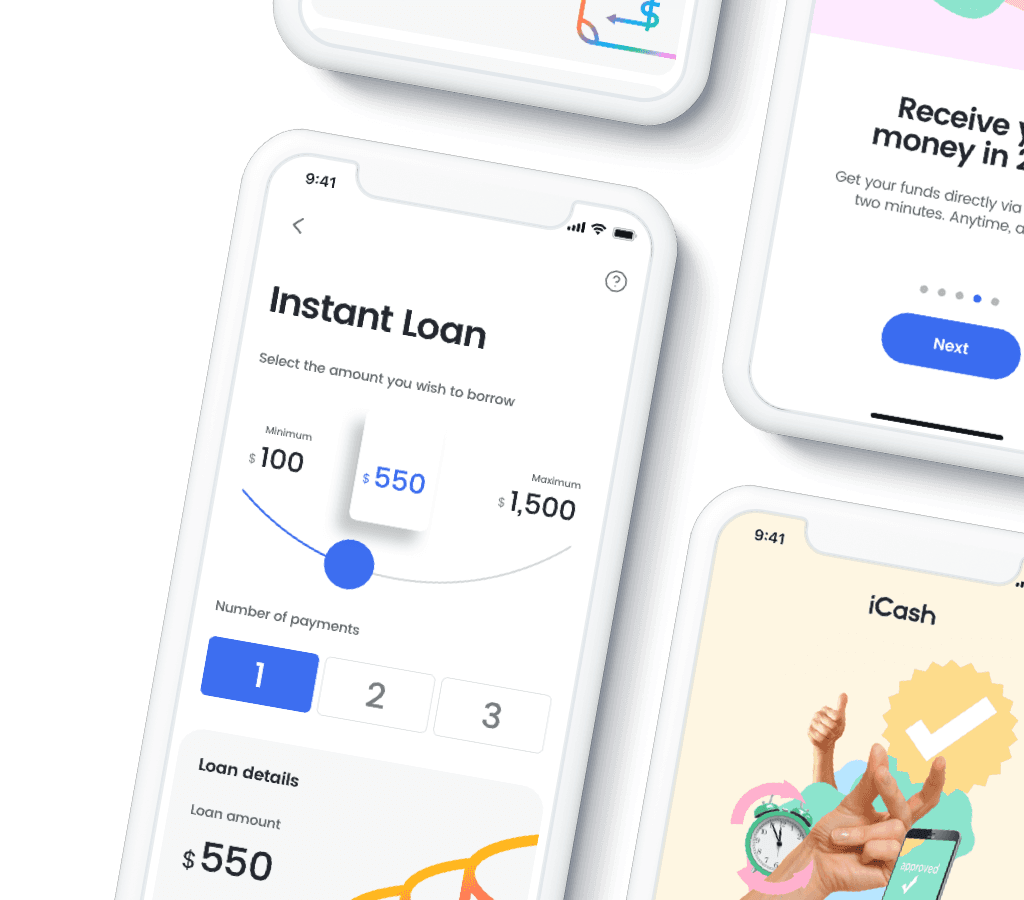
How it works: iCash, a licensed online lender operated by Finabanx Ltd., offers short-term funding with an instant decision and funds via Interac e-Transfer®. iCash doesn't offer a renovation or improvement loan.
Typical amount: Small loan amounts up to $1,500.
Typical cost: $14 per $100 borrowed, repaid on your next payday. See how a payday loan works.
Who it suits: People with a small, urgent cost that can't wait for a larger loan.
Budget | Realistic options | Watch out for |
Under $1,500 | Savings, a card paid off fast, a short-term loan if urgent | Card interest, repeat borrowing |
$1,500 to $5,000 | Individual loan, a 0% promo you can clear | n |
$5,000 to $25,000 | HELOC, or a personal loan with good credit | Variable rates, long terms |
$25,000+ | HELOC, refinance, CMHC Improvement | Your home as collateral |
Once a renovation costs more than about $5,000, your options usually depend on having value in your home, good credit, or both. There isn’t really a quick, low-cost way to borrow a large sum without one or the other. If neither is available, consider scaling back the project, completing it in stages, or saving enough to cover part of the cost upfront.
Yes, but poor credit makes financing harder to find and more expensive when you do find it. Your three main routes are:
Secure the debt against your home: Equity can strengthen an application when your credit isn’t ideal.
Apply with a co-signer: Their history can help you qualify, but they also take on responsibility for repayment.
Choose a smaller loan: Short-term lenders may give more weight to your income, although borrowing limits are lower and fees are higher.
Read more about borrowing with poor credit.
A short-term loan is the wrong tool for a planned remodelling. It's the right tool only for small, urgent, or gap-filling costs.
Good fit: A failed water heater (or something similar), running out of materials at the end of a job, or an emergency repair that can't wait for a HELOC application.
Poor fit: A kitchen remodel, any discretionary spending, or any cost that would need repeat borrowing.
Here's the cost at $14 per $100:
Borrow: $500
Cost of borrowing: $70
Total repayment: $570 on your next payday
Ontario APR disclosure: In Ontario, the maximum cost of borrowing for a payday loan is $14 per $100. On a $500 loan repaid over 14 days, that equals an annual percentage rate of 365%. Try our cost calculator with your own numbers.
Suppose a homeowner is two days away from finishing a bathroom refresh project that they paid for with savings. Their plumber discovers a cracked drain fitting, and it will cost $400 to fix, and it can’t wait. The homeowner gets a short-term loan to cover that urgent cost, and she repays it on her next payday.
A planned remodel is a budgeting decision. An emergency repair is a timing problem, and each calls for different borrowing options.
With a renovation, you have time to gather quotes and apply for a HELOC or loan. A burst pipe or a dead furnace in January needs money in hours. For those, see our guide to emergency or urgent home repairs.
Apply online: Complete the application at icash.ca anytime.
Get an instant decision: You'll find out right away if you're approved.
Receive your funds: Money arrives by Interac e-Transfer within two minutes of approval, 24/7. Learn how funds are received.
Before you apply, read our tips on borrowing responsibly.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Read more reviews.
Have more questions? Check out our full FAQ.